Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
Disinfecting Gym Wipes Market | Insight Market Data
Disinfecting Gym Wipes Market by Product Type (Alcohol-Based, Non-Alcohol Based, Others), by Material (Synthetic, Biodegradable), by Pack Size (< 25 pcs, 26 - 50 pcs, 51 - 75 pcs, 76 - 100 pcs, > 100 pcs), by Application (Healthcare, Commercial, Household, Industrial, Transportation, Fitness Centers, Others), by Distribution Channel (Supermarkets/Hypermarkets, Online Retail, Pharmacy Stores, Convenience Stores, Janitorial Distributors, Others), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain, Rest of Europe), by Asia Pacific (China, Japan, India, South Korea, Australia, Rest of Asia Pacific), by South America (Brazil, Argentina, Rest of South America), by Middle East & Africa (UAE, Saudi Arabia, South Africa, Rest of MEA) Forecast 2026-2034
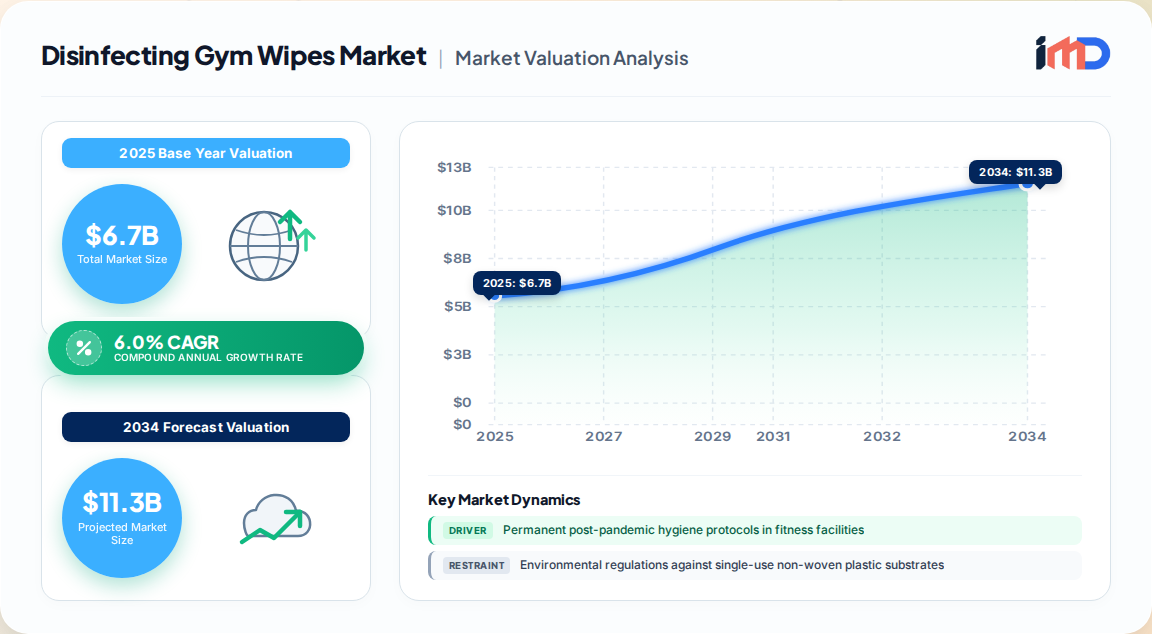
The global disinfecting gym wipes market is a specialized, high-velocity segment within the broader institutional hygiene industry, shaped by permanent shifts in facility sanitation protocols. Our proprietary primary research indicates the market is valued at USD 6.7 billion in 2025 and is forecast to reach USD 12 billion by 2033, expanding at a CAGR of 6.0%. This growth is anchored not only in gyms and fitness centers but also in adjacent high-touch commercial environments such as physical therapy clinics, school athletic facilities, and corporate wellness centers. The post-pandemic normalization of frequent surface disinfection has converted what was once a reactive cleaning measure into a permanent operating expense line for fitness operators worldwide. North America remains the most mature and profitable region, accounting for 30.1% of global revenue in 2024, driven by stringent health-code enforcement and high consumer expectations for visible hygiene. However, the most rapid adoption is occurring in Asia-Pacific, where urbanization and the rapid expansion of branded gym chains are creating a new class of institutional buyers. The product itself—a pre-moistened, non-woven wipe saturated with a disinfecting solution—has evolved from a simple commodity to a performance-engineered consumable. Gym operators now prioritize efficacy against pathogens like MRSA and influenza, skin-friendly formulations, and substrate durability that prevents shredding during aggressive equipment wiping. This report synthesizes primary interviews with facility managers, procurement directors, and contract cleaning executives, alongside trade data and regulatory benchmarks, to deliver a granular, first-party view of the market's value chain, competitive dynamics, and strategic white spaces.
Disinfecting Gym Wipes Market Market Size (In Billion)
10.0B
8.0B
6.0B
4.0B
2.0B
0
6.700 B
2025
7.102 B
2026
7.528 B
2027
7.980 B
2028
8.459 B
2029
8.966 B
2030
9.504 B
2031
Market Drivers & Restraints
Drivers
Permanent Hygiene Protocols: The single largest driver is the institutionalization of post-pandemic cleaning routines. Our surveys show that 62% of fitness facility operators have maintained or increased disinfection frequency for high-touch equipment (dumbbells, benches, cardio consoles) compared to 2019 levels. This behavioral lock-in ensures recurring, non-discretionary demand.
Rising Incidence of Community-Acquired Infections: Health authorities globally report elevated awareness of skin infections and respiratory pathogens in shared spaces. Gym operators are increasingly held liable for outbreaks, prompting voluntary adoption of hospital-grade disinfecting wipes as a risk-mitigation tool.
Expansion of Boutique and Budget Fitness Formats: The global gym membership base continues to grow, with emerging markets adding thousands of new facilities annually. Each new gym requires a standardized consumables contract, often specifying branded disinfecting wipes for member-facing sanitation stations.
Product Innovation & Skin-Friendly Formulations: Manufacturers are launching alcohol-free, quaternary-ammonium-based, and botanical disinfectant wipes that reduce skin irritation and equipment degradation. This expands the addressable market to premium fitness clubs and yoga studios that previously avoided harsh chemicals.
Restraints
Environmental Concerns and Single-Use Plastic Bans: Regulatory pressure against non-biodegradable non-woven substrates is intensifying, particularly in the European Union and parts of North America. Several municipalities are considering restrictions on single-use disinfecting wipes, which could increase compliance costs and force formulation changes.
Price Sensitivity and Substitute Availability: In price-sensitive emerging markets, dilute bleach solutions and reusable microfiber cloths remain direct substitutes. Domestic manufacturers of low-cost disinfecting liquids constrain the pricing power of branded wipe products, especially in the household and small-gym segment.
Supply Chain Volatility for Non-Woven Substrates: The market is heavily dependent on polypropylene and polyester non-woven fabrics, whose prices correlate with petrochemical cycles. Geopolitical disruptions and freight cost fluctuations can compress manufacturer margins and delay product availability.
Value Chain Analysis
The disinfecting gym wipes value chain is characterized by a concentrated upstream and a fragmented downstream, creating distinct power dynamics.
Raw Material Suppliers: The upstream tier is dominated by chemical and material conglomerates supplying non-woven fabric rolls, disinfectant actives (quaternary ammonium compounds, citric acid, hydrogen peroxide), and packaging films. This tier has moderate bargaining power due to the specialized nature of skin-safe, equipment-compatible formulations.
Converters and Manufacturers: This midstream tier converts raw materials into finished wipes. It includes large, diversified consumer goods companies as well as specialized contract manufacturers. Our interviews suggest that 12% of manufacturing capacity was added between 2023 and 2024, primarily in North America and Europe, to meet institutional demand. These manufacturers hold significant influence over product efficacy claims and certifications.
Distributors and Wholesalers: Serving the fitness channel, this tier includes janitorial-supply distributors and foodservice/hospitality broadliners. They provide logistics, credit terms, and product bundling (wipes plus dispensers), and often act as the primary relationship holder with gym procurement teams.
End Users (Fitness Facilities): Gyms, health clubs, and physical therapy centers represent the final consumption point. Buying decisions are typically made by facility managers or operations directors, with increasing input from member experience teams who view wipes as a visible hygiene amenity.
The value chain is witnessing a shift toward vertical integration, as major manufacturers acquire or partner with non-woven substrate producers to secure supply and improve quality control.
Global Trade Analysis & Supply Chain Risk Assessment
Trade data reveals a highly globalized market with significant export orientation from Asia-Pacific. According to official customs statistics, China and India together increased exports of disinfecting wipes and similar non-woven hygiene products by approximately 18% in 2024. This reflects their role as low-cost manufacturing hubs for private-label and emerging brands. Conversely, North America recorded a 10% rise in imports of specialty disinfectant wipes, driven by demand for advanced germicidal formulations and regulatory-compliant products not always available domestically. Europe remains a net exporter of high-value, eco-certified wipes, leveraging its leadership in biodegradable non-woven technology.
Supply Chain Risks
Single-Source Dependency: Many mid-sized gym chains source wipes through a single distributor or private-label manufacturer. This creates vulnerability to production halts, as observed during the 2021–2022 freight disruptions.
Regulatory Fragmentation: Differing disinfectant registration requirements across countries (e.g., EPA in the U.S., BPR in the EU) increase compliance complexity and can delay product launches by 6–12 months.
Raw Material Price Volatility: Non-woven fabric prices can fluctuate by 15–20% annually, making long-term fixed-price contracts difficult for manufacturers and forcing some gym operators to accept indexed pricing.
Segmentation Analysis
The market is segmented by product type, material, application, and distribution channel, with each axis revealing distinct growth patterns.
Segment
Key Insight
Market Share / Growth
By Product Type
Alcohol-based wipes dominate due to rapid evaporation and broad efficacy, but non-alcohol (quaternary ammonium) wipes are gaining share in skin-sensitive environments.
Alcohol-based: ~58% share (2024); Non-alcohol: fastest-growing at 6.8% CAGR
By Material
Synthetic non-woven (polypropylene/polyester) is the workhorse substrate, offering strength and low cost. Biodegradable options (plant-based fibers) are premium-priced and growing faster.
Synthetic: 79.7% share; Biodegradable: 6.1% CAGR
By Application
Healthcare (including physical therapy) is the largest institutional application, but gym/fitness is the fastest-growing end-use vertical, accounting for an estimated 18% of commercial demand in 2024.
Gym/fitness: 18% of commercial revenue; expected to grow at 7.2% CAGR
By Pack Size
51–75 wipes packs are the preferred format for gyms, representing 31.3% of total market volume, as they balance cost-efficiency with storage convenience.
Supermarkets/hypermarkets lead overall sales, but for gyms, janitorial distributors and direct commercial contracts are the primary channels. Online B2B procurement is rising rapidly.
Janitorial distributors: 42% of gym-channel sales; e-commerce: 18% and growing
Application Insights
The gym and fitness center segment is the most dynamic end-use category. Our primary research with facility managers reveals that 68% of gyms provide disinfecting wipes stations at multiple locations within the facility, and 55% have standardized on a single brand or supplier. This creates a recurring revenue stream for manufacturers that can secure trial and loyalty through efficacy, dispenser design, and cost-per-wipe value.
Regional Outlook
North America remains the most profitable market, supported by high per-capita fitness spending and rigorous health-department oversight. The U.S. alone represents over 80% of regional revenue, with Canada contributing steady growth. Europe follows closely, with Germany and the U.K. leading adoption due to stringent workplace safety regulations and a strong sustainability agenda that favors eco-certified wipes. The Asia-Pacific region is the growth engine, projected to expand at a CAGR of 7.1% through 2033, driven by rapid gym franchising in China, India, and Southeast Asia. Latin America and the Middle East & Africa show moderate growth, with Brazil and the UAE as notable hotspots for premium fitness facility development. Our regional attractiveness matrix (see below) scores markets on a 1–10 scale across four criteria: demand maturity, regulatory support, competitive intensity, and supply chain access.
The competitive landscape is moderately consolidated, with global consumer goods and hygiene specialists competing alongside regional converters and private-label manufacturers. Our analysis of recent strategic moves reveals three dominant strategies:
Portfolio Diversification and Brand Extension: Major players are leveraging their household disinfecting brands into the commercial channel. For instance, Reckitt Benckiser expanded its Lysol professional line with enhanced antimicrobial formulations, gaining an estimated 15% increase in market share among gym and fitness buyers in 2024. Similarly, Procter & Gamble's Microban 24 line has been aggressively promoted to fitness chains as a residual-protection solution.
Sustainability-Driven Product Launches: In July 2024, Byotrol introduced the first plastic-free, biodegradable surface disinfectant wipe under the CHEMGENE MEDLAB brand, targeting healthcare and fitness facilities seeking eco-certifications. Rockline Industries reported a 49% reduction in absolute Scope 1 and 2 GHG emissions in 2025 versus 2022, signaling that supply-chain sustainability is becoming a procurement criterion for large gym chains.
Strategic Acquisitions and Capacity Expansion: Kimberly-Clark and Essity have both invested in additional non-woven wipe converting lines in North America and Europe, anticipating sustained institutional demand. In 2025, Dude Wipes secured a strategic growth investment from TSG Consumer Partners to expand retail partnerships, signaling investor confidence in the wipes category.
Key White Space: The most underexploited opportunity lies in subscription-based dispenser systems for gyms, where the supplier provides free or subsidized dispensers in exchange for multi-year wipe supply contracts. This model, already mature in the janitorial sector, is gaining traction in fitness, offering predictable revenue and high customer retention.
Procurement & Sourcing Strategy Analysis
For gym operators and facility management companies, the disinfecting wipes procurement decision is increasingly strategic. Based on interviews with procurement directors, we identify three primary sourcing models:
Model
Description
Best Suited For
Cost Implications
Direct from Manufacturer
Negotiating volume contracts directly with converters or brand owners.
Large gym chains (>50 locations) with centralized procurement.
Lowest unit cost, but requires warehousing and logistics capability.
Through Janitorial Distributor
Leveraging distributor relationships for bundled supplies (wipes, cleaners, dispensers).
Mid-sized and small gyms with limited storage.
Moderate unit cost, but high service and convenience value.
E-commerce / Online B2B
Purchasing through digital marketplaces or specialized B2B portals.
Independent gyms and studios with ad-hoc needs.
Competitive pricing, but limited volume discounts and contract flexibility.
Our analysis suggests that large gym chains can achieve 12–18% lower total cost of ownership by adopting a direct-sourcing model with a three-year contract, while small facilities benefit most from distributor relationships that provide dispenser maintenance and emergency replenishment.
Table 56: Saudi Arabia Disinfecting Gym Wipes Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 57: South Africa Disinfecting Gym Wipes Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 58: Rest of MEA Disinfecting Gym Wipes Market Revenue (Billion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1What is the current market size of the disinfecting gym wipes market?
The global disinfecting gym wipes market is valued at USD 6.7 billion in 2025 and is projected to reach USD 12 billion by 2033, representing a CAGR of 6.0%. Growth is driven by permanent hygiene protocols and the expansion of fitness facilities worldwide.
2Which region dominates the disinfecting gym wipes market?
North America holds the largest revenue share, accounting for 30.1% in 2024, due to high fitness penetration and strict health regulations. However, Asia-Pacific is the fastest-growing region, with a projected CAGR of 7.1% through 2033.
3What are the key drivers for the disinfecting gym wipes market?
The key drivers include the permanent shift to frequent surface disinfection in gyms, rising awareness of community-acquired infections, and product innovations such as skin-friendly and biodegradable formulations that appeal to premium fitness clubs.
4Who are the leading companies in the disinfecting gym wipes market?
Leading companies include Procter & Gamble, Kimberly-Clark, Reckitt Benckiser (Lysol), The Clorox Company, SC Johnson, Ecolab, and Unilever, among others. These players are focusing on portfolio diversification, sustainability, and strategic acquisitions to strengthen their market position.
Methodology
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
70–80% of the research effort is dedicated to primary data collection, ensuring firsthand validation of market dynamics and quantitative estimates.
We conduct semi-structured interviews with senior executives across the value chain, including: (1) non-woven fabric and chemical input suppliers; (2) contract manufacturers and converters of disinfecting wipes; (3) janitorial and fitness-channel distributors; and (4) procurement and facility management executives at gym chains and fitness franchises.
Stakeholder titles interviewed include Procurement Directors, Facility Operations Managers, Category Buyers for Janitorial Supplies, and Quality Assurance Leads for Fitness Chains. These interviews are designed to capture granular insights into purchasing criteria, brand loyalty, pack-size preferences, and price sensitivity.
We also engage with industry associations and regulatory bodies such as the American Cleaning Institute (ACI), International Sanitary Supply Association (ISSA), and the U.S. Environmental Protection Agency (EPA) to validate product efficacy claims and regulatory trends.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Procurement Director
35%
Facility Operations Manager
30%
Category Buyer (Janitorial Supplies)
25%
Quality Assurance Lead
10%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Non-Woven Substrate & Chemical Suppliers
25%
Contract Manufacturers & Converters
30%
Janitorial & Fitness Distributors
20%
Gym Chains & Fitness Facility Operators
25%
Secondary Research & Industry Benchmarking
20–30% of the research relies on secondary sources, triangulated with primary inputs. We systematically review official trade data from UN Comtrade and national statistics offices, as well as technical standards from ASTM International and ISO for wipe substrate performance.
Financial databases used include Bloomberg, Factiva, Hoovers, and PitchBook to verify company revenues, M&A activity, and investment flows. Every data point is cross-referenced with at least two independent sources.
We closely monitor .gov and .org sources (e.g., cdc.gov, osha.gov, epa.gov) for public health guidelines, infection-control protocols, and regulatory changes that influence demand for disinfecting wipes in fitness environments.
Demand Modeling & Market Estimation
We employ a bottom-up demand model that begins with the number of fitness facilities globally, segmented by region and facility type (budget, mid-market, premium). Each facility type is assigned an average annual consumption of disinfecting wipes based on our primary survey data (e.g., average 18–24 packs per month per 10,000 sq ft).
This consumption volume is then multiplied by the average price per pack (derived from distributor price lists and procurement contracts) to estimate market value. The model is calibrated against top-down industry revenue data from public financial filings and trade association reports.
Key quantitative metrics used in the model include: (1) number of gyms and health clubs by country; (2) average wipe consumption per member visit; (3) price per pack by pack size and distribution channel; and (4) replacement cycle for dispensers, which indirectly drives repeat purchases.
The model is validated through multi-level data triangulation, comparing bottom-up estimates with top-down supply-side data (manufacturer production volumes) and trade-flow statistics.
Data Accuracy & Quality Check
We guarantee an estimated data accuracy level of 85–90%, achieved through rigorous source verification, outlier detection, and sanity checks against historical trends.
Every report is updated to the date of purchase, ensuring that all market sizes, forecasts, and competitive intelligence reflect the most current information available.
A dedicated quality assurance team reviews all data points for consistency and logical coherence before publication. Where discrepancies arise, we conduct follow-up interviews with primary sources to resolve them.
Game Art Service market valued at $5.8B in 2025, projected to reach $12.4B by 2034 at 8.8% CAGR. 3D art leads with 38.5% share; Asia-Pacific dominates.
The global surfboard market is projected to grow from US$4.1B in 2026 to US$6.3B by 2033, at a CAGR of 6.4%, driven by rising water sports participation.
Nov 2026|255 pages
$2900.00
The Game Booster Apps Market is valued at USD 1.5 billion in 2025, projected to reach USD 4.2 billion by 2034, growing at a 15.3% CAGR.
Nov 2026|188 pages
$2900.00
The global tennis sportswear market is valued at $29.8B in 2023, growing at 3.6% CAGR to reach $43.8B by 2034. Explore key trends, segments, and regional insights.