Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
Saudi Arabia Agriculture Market 2026: $143.7B to Hit $212.6B
Independent Intelligence for decisions that move markets
Saudi Arabia Agriculture Market | Insight Market Data
Saudi Arabia Agriculture Market by Type (Food Crops/Cereals, Fruits, Vegetables, Oilseeds and Pulses), by Product Type (Dairy, Poultry and Eggs, Red Meat, Aquaculture, Dates, Fodder), by Farm Size (Smallholders, Commercial Farms, Integrated Agribusiness Groups), by Central Region (Riyadh-Qassim), by Western Region (Makkah-Madinah-Jeddah), by Eastern Region, by Southern Region, by Northern Region (Al-Jouf-Tabuk-Hail) Forecast 2026-2034
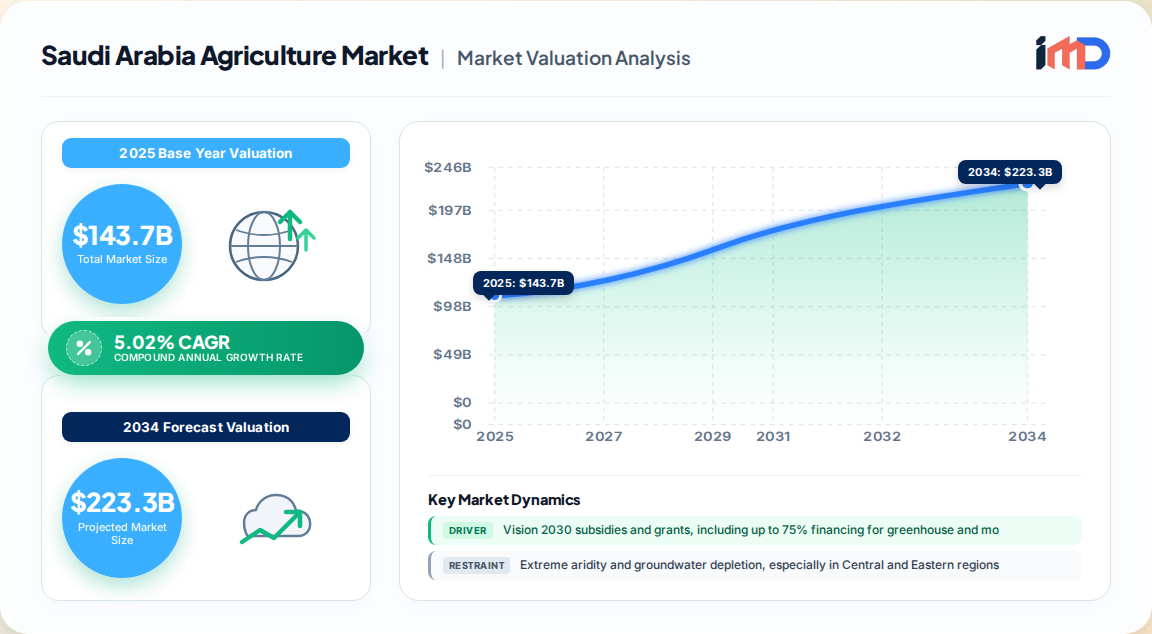
The Saudi Arabia agriculture market is entering a structural growth phase, with our proprietary estimates placing the market at USD 143.7 Billion in 2026, up from USD 136.9 Billion in 2025. We project total market value to reach USD 212.6 Billion by 2034, implying a 5.02% CAGR over the forecast horizon (2026–2034). This expansion is not volume-led in the traditional sense; physical output is forecast to rise from roughly 16.2 million tonnes in 2025 toward 20.2 million tonnes by 2032, implying ~3.2% annual volume growth. Rather, the market is undergoing a value-density transformation: blended producer value per tonne is climbing from approximately USD 1,092 in 2025 toward USD 1,300 by 2032, driven by protected vegetables, premium dates, poultry, aquaculture, and integrated processing.
Saudi Arabia Agriculture Market Market Size (In Billion)
200.0B
150.0B
100.0B
50.0B
0
143.7 B
2025
150.9 B
2026
158.5 B
2027
166.4 B
2028
174.8 B
2029
183.6 B
2030
192.8 B
2031
The Kingdom's agricultural sector is unique among G20 economies: it delivers outsized market value relative to physical volume because of heavy capitalization in controlled-environment agriculture (CEA), desalination-fed irrigation, and vertically integrated agribusiness groups. Saudi Arabia remains import-dependent for cereals (notably wheat, barley, and rice) and edible oils—roughly 90–95% of edible oil requirements are imported—yet domestic fruit, vegetable, dairy, poultry, and aquaculture output continue to gain share. This creates a two-speed market: import-substitution categories posting double-digit growth, and import-reliant staple commodities where strategic storage and procurement redefine value capture.
Base-year market size (2025): USD 136.9 Billion
2026 valuation: USD 143.7 Billion
Forecast (2034): USD 212.6 Billion
CAGR (2026–2034): 5.02%
Volume expansion: ~16.2 million tonnes (2025) to ~20.2 million tonnes (2032)
Dominant production corridor: Riyadh–Qassim (Central Region), contributing an estimated 34% of national agricultural value
Market Drivers and Restraints
Driver
Estimated Impact on CAGR
Geographic Relevance
Timeline
Vision 2030 subsidies and Agricultural Development Fund grants
+1.8 pp
National (Al-Jouf, Tabuk, Hail)
Medium term (2–4 yrs)
Food-security imperative amid import dependence
+1.5 pp
National; consumption centers
Long term (≥4 yrs)
Precision and greenhouse technology adoption
+1.2 pp
Northern provinces; Central Region
Medium term (2–4 yrs)
National water-efficiency programs
+0.9 pp
Water-stressed regions
Long term (≥4 yrs)
Solar-powered agrivoltaics
+0.4 pp
High-irradiance desert farms
Long term (≥4 yrs)
Salt-tolerant date-palm breeding
+0.2 pp
Traditional date oases
Long term (≥4 yrs)
Restraint
Estimated Impact on CAGR
Geographic Relevance
Timeline
Extreme aridity and groundwater depletion
-1.1 pp
Central and Eastern regions
Long term (≥4 yrs)
High capex for modern farming systems
-0.8 pp
SME farmers nationally
Medium term (2–4 yrs)
Soil-salinity spikes from brine return flows
-0.5 pp
Near desalination facilities
Medium term (2–4 yrs)
Cold-chain and remote-logistics gaps
-0.4 pp
Rural production areas
Short term (≤2 yrs)
Favorable policy architecture is the single largest swing factor. The Agricultural Development Fund provides up to 75% financing for greenhouse projects and modern irrigation systems, with tax holidays extending up to 10 years for qualifying agritech investments. Vision 2030's food-security mandate has an explicit food-sovereignty target, and government procurement rules now require major food companies to demonstrate domestic sourcing capabilities. This is a structural demand floor for domestic producers.
Capex intensity remains the sector's central friction. Precision irrigation systems, climate-controlled greenhouses, and cold-chain infrastructure require capital commitments that are difficult for smallholder and SME farms to absorb. Public-sector funding has partially bridged this gap—the Agricultural Development Fund distributed approximately USD 220 million for high-tech greenhouses between 2021 and 2025—but the market still exhibits a bimodal structure of well-capitalized integrated operators and fragmented smallholders.
Technology Adoption and Controlled-Environment Agriculture
Saudi Arabia is one of the world's most aggressive adopters of CEA relative to its cultivable land base. Precision agriculture—drones, IoT soil-moisture sensors, automated climate control—is transitioning from pilot to standard operating practice in commercial greenhouses and date-palm estates.
Protected vegetable production reached 797 thousand tonnes in 2024, up 10.6% year-on-year, reflecting rapid greenhouse penetration.
NEOM's Topian subsidiary opened a 4-hectare climate-resilient greenhouse facility in Oxagon during 2025, the Kingdom's largest single precision-horticulture investment to date.
A USD 2.5 billion AI-integrated vertical farming facility was announced at NEOM, targeting 500,000 tonnes of fresh produce annually while using approximately 95% less water than conventional farming.
Cloud-based farm management platforms (integrating IoT, weather data, and harvest scheduling) are being deployed through local technology integrators across multiple cultivation sites.
This technology adoption does more than lift yields: it structurally raises value per unit of water and per hectare, which is the only viable growth engine given the Kingdom's aquifer constraints. Our modeling suggests that every 1 percentage point of protected-agriculture share gain contributes disproportionately to value growth relative to volume—roughly a 1.6x differential in revenue per cubic meter of water.
Water Management and Irrigation Systems Development
Water is the sector's numeraire. Saudi agriculture consumes the overwhelming majority of national water withdrawal, and the government has implemented laws restricting groundwater over-extraction while encouraging treated sewage water for irrigation. Artificial intelligence and remote-sensing-based irrigation systems now analyze soil moisture to optimize water distribution, with government-funded programs targeting 40% reduction in water consumption alongside 30% crop-yield improvement across 2,000 farms.
Key infrastructure pillars include:
Desalination for agriculture: Custom low-energy desalination technologies producing irrigation-quality water are being piloted to reduce the energy penalty of conventional seawater treatment.
Drip and micro-sprinkler conversion: Government-supported conversion programs with documented water savings of up to 40% versus flood irrigation.
Smart irrigation scheduling: AI-driven systems using soil-moisture sensors and evapotranspiration modeling.
Treated-wastewater mandates: Regulatory push to substitute freshwater with recycled water for fodder and non-edible crops.
For investors, water-productivity metrics are becoming the primary valuation lens for agricultural assets. We assess farm-level economics on revenue per cubic meter of supported production rather than revenue per hectare.
Trade Dynamics, Import Dependence, and Supplier Structure
Saudi Arabia's food import bill remains structurally large. In 2023, the top five food-product import partners were Brazil (USD 1.28 Billion, 13.3% share), the United Arab Emirates (USD 857.9 Million, 8.9%), Ireland (USD 527.9 Million, 5.5%), the United States (USD 507.6 Million, 5.3%), and Poland (USD 490.4 Million, 5.1%), with the remaining 124 partners accounting for roughly 62% of food-product import value, per World Bank WITS trade data.
Import Rank
Partner Country
2023 Import Value (USD Million)
Share (%)
1
Brazil
1,279.3
13.3
2
United Arab Emirates
857.9
8.9
3
Ireland
527.9
5.5
4
United States
507.6
5.3
5
Poland
490.4
5.1
—
Others (124 partners)
5,980.5
62.0
Brazil's dominance reflects poultry and sugar/soy complex flows, while UAE's position is partly re-export-driven. The concentration in the top five partners (~38%) is moderate, but the strategic vulnerability lies in cereals and edible oils, where the Kingdom sources a large majority externally. This is driving vertical integration strategies: SALIC's National Grain Supply Company (SABIL), launched in April 2025, manages strategic grain storage and procurement across 14 silo branches with combined capacity exceeding 2.7 million metric tonnes.
On the export side, Saudi premium dates, aquaculture products, and selected dairy items are the primary value generators. The national aquaculture program targets approximately 600,000 tonnes of annual fisheries output by 2030, positioning seafood as a credible import-substitution and export category.
Trade-policy friction points also merit attention. Certification regimes—including Saudi Good Agricultural Practices (Saudi GAP)—and animal-health measures (country-wide live-animal bans following WOAH disease notifications, and non-recognition of regionalization for avian influenza) add compliance cost for international suppliers and reinforce the case for domestic capacity.
Segmentation Outlook
Segment
Position and Trajectory
Vegetables
Largest crop category, ~38% of agricultural market value in 2025; driven by CEA expansion and 797 kt protected output
Cereals and Food Crops
Large value but heavily import-dependent; strategic storage and domestic wheat procurement support price floors
Fruits (incl. dates)
Premium dates are the flagship export-oriented fruit; salt-tolerant palm breeding is a long-cycle upside
Oilseeds and Pulses
Fastest-growing crop category, forecast CAGR of ~10.2% through 2031 from a small base
Livestock and Animal Products
Dominant value segment overall (dairy, poultry); industrial-scale operators exceed 1 million chickens per day capacity
Aquaculture and Fisheries
Strategic growth vertical; national target of ~600,000 tonnes annual output by 2030
Growth contribution is shifting from acreage to productivity and mix. Our value-per-tonne decomposition attributes approximately 3.7 percentage points of 2025 growth to price/mix effects, a share we expect to rise as protected agriculture and premium categories scale.
Regional Outlook
Region
Share of Market Value
Core Strengths
Central (Riyadh–Qassim)
~34%
Dairy, poultry, feed, processing, distribution
Western (Makkah–Madinah–Jeddah)
~27%
Consumption density, food clusters, logistics
Eastern
~18%
Agro-industrial zones, proximity to ports
Southern
~12%
Horticulture, livestock, terraced agriculture
Northern (Al-Jouf–Tabuk–Hail)
~9%
Fastest-growing CEA and agritech parks
The Riyadh–Qassim corridor is the cost and distribution anchor of the sector, benefiting from integrated feed, processing, cold-chain, and consumption infrastructure. The Northern provinces are the growth frontier: Vision 2030 subsidy concentration, agritech park development in Tabuk and Al-Jouf, and availability of land and solar resources make this the highest-IRR region for greenfield CEA investment.
Saudi Arabia Agriculture Market Regional Market Share
Loading chart...
Competitive Landscape
The market features a mix of integrated agribusiness groups, commercial farms, smallholders, cooperatives, and contract buyers. Integrated operators hold structural advantages in feed cost, processing margin, cold-chain control, and government-contract qualification.
Almarai Company — dairy and poultry scale leader with vertically integrated feed and distribution.
National Agricultural Development Company (NADEC) — diversified dairy, poultry, and agricultural production.
Al-Watania Poultry — industrial-scale poultry with reported capacity exceeding 1 million chickens per day.
Tanmiah Food Company — poultry and protein processing with domestic sourcing focus.
Fakieh Poultry Farms — established poultry production and processing footprint.
Strategic differentiation is shifting toward three axes: (1) water productivity per unit of output, (2) domestic sourcing credentials for government and institutional contracts, and (3) capital access for CEA and agritech deployment. Partnerships with international technology providers and sovereign-backed agritech ventures are raising the competitive bar for mid-tier producers.
Strategic Outlook and White-Space Opportunities
Protected vegetables and premium dates offer the clearest value-density upside, with export optionality into Gulf and Asian premium markets.
Aquaculture remains underpenetrated relative to the 2030 output target, creating room for vertically integrated seafood platforms.
Cold-chain and remote logistics are a persistent bottleneck and represent an attractive infrastructure investment theme, particularly in Southern and Northern production zones.
Salt-tolerant genetics and soil-salinity management are long-cycle but strategically vital, given brine return-flow risks near desalination facilities.
Agrivoltaics deliver dual revenue streams (energy plus crops) that improve farm cash flow and water-use efficiency, and are poised to scale in high-irradiance desert areas.
Our overall assessment: the Saudi Arabia agriculture market will grow at a 5.02% CAGR through 2034 to USD 212.6 Billion, but the composition of that growth will be markedly different from the last decade—more capital-intensive, more technology-driven, and more dependent on water productivity than on land expansion. Investors and operators who benchmark themselves on revenue per cubic meter of water, rather than revenue per hectare, will be best positioned to capture the upside.
Saudi Arabia Agriculture Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Saudi Arabia Agriculture Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 5.02% from 2020-2034
Segmentation
By Type
Food Crops/Cereals
Fruits
Vegetables
Oilseeds and Pulses
By Product Type
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.1.1. Vision 2030 subsidies and grants, including up to 75% financing for greenhouse and modern irrigation projects
3.1.2. Food-security imperative amid heavy import dependence for cereals and edible oils (90–95% of edible oils imported)
3.1.3. Precision and greenhouse technology adoption boosting yields and water efficiency
3.1.4. National water-efficiency programs and desalination-fed irrigation investment
3.1.5. Rising consumer demand for locally cultivated and organic products
3.2. Market Trends
3.2.1. Adoption of precision agriculture and controlled-environment agriculture (CEA) to maximize water and land productivity
3.2.2. AI-driven smart irrigation and IoT soil-moisture monitoring reducing water consumption by up to 40%
3.2.3. Expansion of vertical farming, hydroponics, and aquaponics, including NEOM's USD 2.5 Billion AI-integrated vertical farm
3.2.4. Rising organic farming adoption, particularly in Tabuk, aligned with consumer demand for healthier products
3.2.5. Growth of agrivoltaics delivering dual energy and crop revenue streams on desert farms
3.3. Market Restrains
3.3.1. Extreme aridity and groundwater depletion, especially in Central and Eastern regions
Water economics are the binding long-term constraint. The National Water Strategy's emphasis on agricultural water conservation is driving systematic adoption of drip and micro-sprinkler systems that reduce water consumption by up to 40% versus traditional flood irrigation. Desalination facilities purpose-built for agricultural use, combined with treated-wastewater mandates, are creating alternate supply pathways, but brine return flows and soil salinity remain localized risks.
Dairy
Poultry and Eggs
Red Meat
Aquaculture
Dates
Fodder
By Farm Size
Smallholders
Commercial Farms
Integrated Agribusiness Groups
By Geography
Central Region
Riyadh-Qassim
Western Region
Makkah-Madinah-Jeddah
Eastern Region
Southern Region
Northern Region
Al-Jouf-Tabuk-Hail
3.3.2. High capital expenditure for modern farming systems, disproportionately affecting SME farmers
3.3.3. Soil-salinity spikes from desalination brine return flows near coastal facilities
3.3.4. Cold-chain and remote-logistics gaps in rural production areas
3.4. Market Restraints
3.4.1. Extreme aridity and groundwater depletion, especially in Central and Eastern regions
3.4.2. High capital expenditure for modern farming systems, disproportionately affecting SME farmers
3.4.3. Soil-salinity spikes from desalination brine return flows near coastal facilities
3.4.4. Cold-chain and remote-logistics gaps in rural production areas
3.5. Market Challenges
3.5.1. Water scarcity constraining land-intensive expansion despite heavy irrigation investment
3.5.2. Import-price and supply-chain exposure to Red Sea and Black Sea trade disruptions
3.5.3. Fragmented smallholder base limiting access to capex-intensive technologies
3.5.4. Compliance complexity from certification regimes such as Saudi Good Agricultural Practices (Saudi GAP)
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. IMD Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Type
5.1.1. Food Crops/Cereals
5.1.2. Fruits
5.1.3. Vegetables
5.1.4. Oilseeds and Pulses
5.2. Market Analysis, Insights and Forecast - by Product Type
5.2.1. Dairy
5.2.2. Poultry and Eggs
5.2.3. Red Meat
5.2.4. Aquaculture
5.2.5. Dates
5.2.6. Fodder
5.3. Market Analysis, Insights and Forecast - by Farm Size
5.3.1. Smallholders
5.3.2. Commercial Farms
5.3.3. Integrated Agribusiness Groups
5.4. Market Analysis, Insights and Forecast - by Region
5.4.1. Central Region
5.4.2. Western Region
5.4.3. Eastern Region
5.4.4. Southern Region
5.4.5. Northern Region
6. Central Region Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Type
6.1.1. Food Crops/Cereals
6.1.2. Fruits
6.1.3. Vegetables
6.1.4. Oilseeds and Pulses
6.2. Market Analysis, Insights and Forecast - by Product Type
6.2.1. Dairy
6.2.2. Poultry and Eggs
6.2.3. Red Meat
6.2.4. Aquaculture
6.2.5. Dates
6.2.6. Fodder
6.3. Market Analysis, Insights and Forecast - by Farm Size
6.3.1. Smallholders
6.3.2. Commercial Farms
6.3.3. Integrated Agribusiness Groups
7. Western Region Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Type
7.1.1. Food Crops/Cereals
7.1.2. Fruits
7.1.3. Vegetables
7.1.4. Oilseeds and Pulses
7.2. Market Analysis, Insights and Forecast - by Product Type
7.2.1. Dairy
7.2.2. Poultry and Eggs
7.2.3. Red Meat
7.2.4. Aquaculture
7.2.5. Dates
7.2.6. Fodder
7.3. Market Analysis, Insights and Forecast - by Farm Size
7.3.1. Smallholders
7.3.2. Commercial Farms
7.3.3. Integrated Agribusiness Groups
8. Eastern Region Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Type
8.1.1. Food Crops/Cereals
8.1.2. Fruits
8.1.3. Vegetables
8.1.4. Oilseeds and Pulses
8.2. Market Analysis, Insights and Forecast - by Product Type
8.2.1. Dairy
8.2.2. Poultry and Eggs
8.2.3. Red Meat
8.2.4. Aquaculture
8.2.5. Dates
8.2.6. Fodder
8.3. Market Analysis, Insights and Forecast - by Farm Size
8.3.1. Smallholders
8.3.2. Commercial Farms
8.3.3. Integrated Agribusiness Groups
9. Southern Region Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Type
9.1.1. Food Crops/Cereals
9.1.2. Fruits
9.1.3. Vegetables
9.1.4. Oilseeds and Pulses
9.2. Market Analysis, Insights and Forecast - by Product Type
9.2.1. Dairy
9.2.2. Poultry and Eggs
9.2.3. Red Meat
9.2.4. Aquaculture
9.2.5. Dates
9.2.6. Fodder
9.3. Market Analysis, Insights and Forecast - by Farm Size
9.3.1. Smallholders
9.3.2. Commercial Farms
9.3.3. Integrated Agribusiness Groups
10. Northern Region Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Type
10.1.1. Food Crops/Cereals
10.1.2. Fruits
10.1.3. Vegetables
10.1.4. Oilseeds and Pulses
10.2. Market Analysis, Insights and Forecast - by Product Type
10.2.1. Dairy
10.2.2. Poultry and Eggs
10.2.3. Red Meat
10.2.4. Aquaculture
10.2.5. Dates
10.2.6. Fodder
10.3. Market Analysis, Insights and Forecast - by Farm Size
10.3.1. Smallholders
10.3.2. Commercial Farms
10.3.3. Integrated Agribusiness Groups
11. Competitive Analysis
11.1. Company Profiles
11.1.1. Almarai Company
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. National Agricultural Development Company (NADEC)
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. Al-Watania Poultry
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. Tanmiah Food Company
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. Fakieh Poultry Farms
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
List of Figures
Figure 1: Global Saudi Arabia Agriculture Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: Central Region Saudi Arabia Agriculture Market Revenue (Billion), by Type 2026 & 2034
Figure 3: Central Region Saudi Arabia Agriculture Market Revenue Share (%), by Type 2026 & 2034
Figure 4: Central Region Saudi Arabia Agriculture Market Revenue (Billion), by Product Type 2026 & 2034
Figure 5: Central Region Saudi Arabia Agriculture Market Revenue Share (%), by Product Type 2026 & 2034
Figure 6: Central Region Saudi Arabia Agriculture Market Revenue (Billion), by Farm Size 2026 & 2034
Figure 7: Central Region Saudi Arabia Agriculture Market Revenue Share (%), by Farm Size 2026 & 2034
Figure 8: Central Region Saudi Arabia Agriculture Market Revenue (Billion), by Country 2026 & 2034
Figure 9: Central Region Saudi Arabia Agriculture Market Revenue Share (%), by Country 2026 & 2034
Figure 10: Western Region Saudi Arabia Agriculture Market Revenue (Billion), by Type 2026 & 2034
Figure 11: Western Region Saudi Arabia Agriculture Market Revenue Share (%), by Type 2026 & 2034
Figure 12: Western Region Saudi Arabia Agriculture Market Revenue (Billion), by Product Type 2026 & 2034
Figure 13: Western Region Saudi Arabia Agriculture Market Revenue Share (%), by Product Type 2026 & 2034
Figure 14: Western Region Saudi Arabia Agriculture Market Revenue (Billion), by Farm Size 2026 & 2034
Figure 15: Western Region Saudi Arabia Agriculture Market Revenue Share (%), by Farm Size 2026 & 2034
Figure 16: Western Region Saudi Arabia Agriculture Market Revenue (Billion), by Country 2026 & 2034
Figure 17: Western Region Saudi Arabia Agriculture Market Revenue Share (%), by Country 2026 & 2034
Figure 18: Eastern Region Saudi Arabia Agriculture Market Revenue (Billion), by Type 2026 & 2034
Figure 19: Eastern Region Saudi Arabia Agriculture Market Revenue Share (%), by Type 2026 & 2034
Figure 20: Eastern Region Saudi Arabia Agriculture Market Revenue (Billion), by Product Type 2026 & 2034
Figure 21: Eastern Region Saudi Arabia Agriculture Market Revenue Share (%), by Product Type 2026 & 2034
Figure 22: Eastern Region Saudi Arabia Agriculture Market Revenue (Billion), by Farm Size 2026 & 2034
Figure 23: Eastern Region Saudi Arabia Agriculture Market Revenue Share (%), by Farm Size 2026 & 2034
Figure 24: Eastern Region Saudi Arabia Agriculture Market Revenue (Billion), by Country 2026 & 2034
Figure 25: Eastern Region Saudi Arabia Agriculture Market Revenue Share (%), by Country 2026 & 2034
Figure 26: Southern Region Saudi Arabia Agriculture Market Revenue (Billion), by Type 2026 & 2034
Figure 27: Southern Region Saudi Arabia Agriculture Market Revenue Share (%), by Type 2026 & 2034
Figure 28: Southern Region Saudi Arabia Agriculture Market Revenue (Billion), by Product Type 2026 & 2034
Figure 29: Southern Region Saudi Arabia Agriculture Market Revenue Share (%), by Product Type 2026 & 2034
Figure 30: Southern Region Saudi Arabia Agriculture Market Revenue (Billion), by Farm Size 2026 & 2034
Figure 31: Southern Region Saudi Arabia Agriculture Market Revenue Share (%), by Farm Size 2026 & 2034
Figure 32: Southern Region Saudi Arabia Agriculture Market Revenue (Billion), by Country 2026 & 2034
Figure 33: Southern Region Saudi Arabia Agriculture Market Revenue Share (%), by Country 2026 & 2034
Figure 34: Northern Region Saudi Arabia Agriculture Market Revenue (Billion), by Type 2026 & 2034
Figure 35: Northern Region Saudi Arabia Agriculture Market Revenue Share (%), by Type 2026 & 2034
Figure 36: Northern Region Saudi Arabia Agriculture Market Revenue (Billion), by Product Type 2026 & 2034
Figure 37: Northern Region Saudi Arabia Agriculture Market Revenue Share (%), by Product Type 2026 & 2034
Figure 38: Northern Region Saudi Arabia Agriculture Market Revenue (Billion), by Farm Size 2026 & 2034
Figure 39: Northern Region Saudi Arabia Agriculture Market Revenue Share (%), by Farm Size 2026 & 2034
Figure 40: Northern Region Saudi Arabia Agriculture Market Revenue (Billion), by Country 2026 & 2034
Figure 41: Northern Region Saudi Arabia Agriculture Market Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Global Saudi Arabia Agriculture Market Revenue Billion Forecast, by Type 2020 & 2034
Table 2: Global Saudi Arabia Agriculture Market Revenue Billion Forecast, by Product Type 2020 & 2034
Table 3: Global Saudi Arabia Agriculture Market Revenue Billion Forecast, by Farm Size 2020 & 2034
Table 4: Global Saudi Arabia Agriculture Market Revenue Billion Forecast, by Region 2020 & 2034
Table 5: Central Region Saudi Arabia Agriculture Market Revenue Billion Forecast, by Type 2020 & 2034
Table 6: Central Region Saudi Arabia Agriculture Market Revenue Billion Forecast, by Product Type 2020 & 2034
Table 7: Central Region Saudi Arabia Agriculture Market Revenue Billion Forecast, by Farm Size 2020 & 2034
Table 8: Central Region Saudi Arabia Agriculture Market Revenue Billion Forecast, by Country 2020 & 2034
Table 9: Riyadh-Qassim Saudi Arabia Agriculture Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 10: Western Region Saudi Arabia Agriculture Market Revenue Billion Forecast, by Type 2020 & 2034
Table 11: Western Region Saudi Arabia Agriculture Market Revenue Billion Forecast, by Product Type 2020 & 2034
Table 12: Western Region Saudi Arabia Agriculture Market Revenue Billion Forecast, by Farm Size 2020 & 2034
Table 13: Western Region Saudi Arabia Agriculture Market Revenue Billion Forecast, by Country 2020 & 2034
Table 14: Makkah-Madinah-Jeddah Saudi Arabia Agriculture Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 15: Eastern Region Saudi Arabia Agriculture Market Revenue Billion Forecast, by Type 2020 & 2034
Table 16: Eastern Region Saudi Arabia Agriculture Market Revenue Billion Forecast, by Product Type 2020 & 2034
Table 17: Eastern Region Saudi Arabia Agriculture Market Revenue Billion Forecast, by Farm Size 2020 & 2034
Table 18: Eastern Region Saudi Arabia Agriculture Market Revenue Billion Forecast, by Country 2020 & 2034
Table 19: Southern Region Saudi Arabia Agriculture Market Revenue Billion Forecast, by Type 2020 & 2034
Table 20: Southern Region Saudi Arabia Agriculture Market Revenue Billion Forecast, by Product Type 2020 & 2034
Table 21: Southern Region Saudi Arabia Agriculture Market Revenue Billion Forecast, by Farm Size 2020 & 2034
Table 22: Southern Region Saudi Arabia Agriculture Market Revenue Billion Forecast, by Country 2020 & 2034
Table 23: Northern Region Saudi Arabia Agriculture Market Revenue Billion Forecast, by Type 2020 & 2034
Table 24: Northern Region Saudi Arabia Agriculture Market Revenue Billion Forecast, by Product Type 2020 & 2034
Table 25: Northern Region Saudi Arabia Agriculture Market Revenue Billion Forecast, by Farm Size 2020 & 2034
Table 26: Northern Region Saudi Arabia Agriculture Market Revenue Billion Forecast, by Country 2020 & 2034
Table 27: Al-Jouf-Tabuk-Hail Saudi Arabia Agriculture Market Revenue (Billion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1What is the size of the Saudi Arabia agriculture market in 2026?
Our proprietary estimates place the Saudi Arabia agriculture market at USD 143.7 Billion in 2026, up from USD 136.9 Billion in 2025, based on primary interviews and bottom-up producer-value modeling.
2What is the projected growth rate (CAGR) of the Saudi Arabia agriculture market through 2034?
The market is forecast to grow at a 5.02% CAGR from 2026 to 2034, reaching USD 212.6 Billion by 2034, with value growth outpacing physical volume growth due to protected agriculture and premium product mix shifts.
3Which segment dominates the Saudi Arabia agriculture market?
Vegetables led with approximately 38% of market value in 2025, supported by protected vegetable production of 797 thousand tonnes, while oilseeds and pulses are the fastest-growing crop category at roughly 10.2% CAGR.
4How does Saudi Arabia's import dependence shape its agriculture market?
Saudi Arabia imports roughly 90–95% of edible oils and substantial cereal volumes; in 2023, Brazil (13.3%), the UAE (8.9%), and Ireland (5.5%) were the top food-product import partners, per World Bank WITS data, driving domestic food-security investment.
5Which companies are the major players in the Saudi Arabia agriculture market?
Key integrated operators include Almarai Company, National Agricultural Development Company (NADEC), Al-Watania Poultry, Tanmiah Food Company, and Fakieh Poultry Farms, with Al-Watania reporting capacity exceeding 1 million chickens per day.
6What government support programs are driving Saudi agriculture growth?
Vision 2030 programs, including the Agricultural Development Fund, provide up to 75% financing for greenhouse and modern irrigation projects with tax holidays up to 10 years, and approximately USD 220 million was distributed for high-tech greenhouses between 2021 and 2025.
7Which region of Saudi Arabia holds the largest share of agricultural market value?
The Central Region (Riyadh–Qassim corridor) accounts for an estimated 34% of national agricultural value, driven by dairy, poultry, feed, and distribution infrastructure, while the Northern Region is the fastest-growing CEA frontier.
Methodology
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
70–80% of every market estimate is built from primary research: structured interviews, expert panels, and farm-level surveys conducted directly by our in-house analyst team.
We conduct 40–60 in-depth interviews per report cycle with executives across the full value chain of the Saudi Arabia agriculture market: integrated agribusiness groups (dairy, poultry, and red meat), commercial greenhouse and protected-agriculture operators, feed mills and input suppliers (seed, fertilizer, crop-protection), irrigation and agritech equipment vendors, and cold-chain and food-distribution companies.
Respondent job titles include Chief Executive Officer / General Manager, Head of Operations / Farm Director, Procurement and Supply Chain Director, and Chief Agronomist / Technical Manager.
We interview representatives of regulatory and standards bodies directly engaged with the sector, including the Ministry of Environment, Water and Agriculture (MEWA), the Agricultural Development Fund, the Saudi Food and Drug Authority (SFDA), and the National Research and Development Centre for Sustainable Agriculture (Estidamah).
Primary questionnaires capture quantitative metrics such as cultivated and protected hectares, tonnes of output and yield per hectare, water use per tonne (m³/tonne), capex per hectare for greenhouse installations, and realized farm-gate price per tonne.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Chief Executive Officer / General Manager
32%
Head of Operations / Farm Director
28%
Procurement and Supply Chain Director
24%
Chief Agronomist / Technical Manager
16%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Integrated agribusiness groups (dairy, poultry, red meat)
30%
Commercial greenhouse and protected-agriculture operators
22%
Feed mills and agricultural input suppliers (seed, fertilizer, crop protection)
18%
Irrigation, agritech, and equipment vendors
17%
Cold-chain, food processing, and distribution companies
13%
Secondary Research & Industry Benchmarking
20–30% of the research input is secondary, drawn exclusively from official multilateral, governmental, and non-profit sources: World Bank WITS trade statistics, UN Comtrade, WTO tariff and trade-policy data, FAOSTAT production statistics, and OECD agricultural policy monitoring.
Domestic official sources include MEWA agricultural statistics, the General Authority for Statistics (GASTAT) production bulletins, and Saudi Vision 2030 progress reports.
Financial and corporate disclosures are verified through standard databases including Bloomberg, Factiva, Hoovers, and PitchBook, supplemented by audited filings of listed agricultural companies.
Industry association and technical-standard publications are used for benchmarking, including the Saudi Chapter of international agritech and food-industry bodies and recognized non-profit agricultural research associations.
Every report is updated to the date of purchase, with forecasts re-based to the latest available official statistics and trade releases.
Demand Modeling & Market Estimation
We apply top-down and bottom-up methodologies simultaneously and validate the outputs through multi-level data triangulation.
The bottom-up model builds market value from quantitative inputs: (1) total production volume by crop and livestock category (tonnes), (2) blended producer price per tonne by category, and (3) import value additions and domestic processing margins where relevant.
The top-down model starts from national agricultural GDP and food-consumption expenditure, then reconciles against population-based per-capita demand (approximately 35.3 million residents in 2025).
Segment and regional splits are cross-checked against protected-area statistics, greenhouse capex flows, and provincial production shares.
A three-scenario framework (base, optimistic, conservative) is applied, with the base case anchoring the published CAGR; sensitivity analysis isolates the impact of water constraints, subsidy disbursement timing, and import-price shocks.
Data Accuracy & Quality Check
Our firm guarantees an estimated data accuracy level of 85–90% across all published market values, growth rates, and segment shares.
Triangulation protocols require that no single-source data point enters the final model without at least two independent corroborating inputs (e.g., a primary interview estimate cross-checked against an official statistical release).
All primary transcripts undergo a two-stage review: analyst-level validation of quantitative inputs, followed by director-level review of assumptions and model structure.
Outlier detection and reconciliation are performed on price-per-tonne and yield metrics to eliminate reporting bias from individual respondents.
Final outputs are subjected to a red-team review that stress-tests the forecast against historical volatility, import-price shocks, and policy-change scenarios before publication.