Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
India Agricultural Tractor Market Size, Growth & Forecast 2031 | Insight Market Data
India Agricultural Tractor Market
Agriculture / MARKET REPORT
India Agricultural Tractor Market | Insight Market Data
India Agricultural Tractor Market by Power Output (Less than 40 HP, 40-100 HP, Above 100 HP), by Drive Type (2-Wheel Drive, 4-Wheel Drive), by Application (Plowing and Cultivating, Planting, Haying and Forage, Sprayers, Harvesting, Hauling, Row Crop), by Engine Type (Internal Combustion Engine, Electric Engine, Hybrid Engine), by North (Uttar Pradesh, Punjab, Haryana, Rajasthan), by West (Maharashtra, Gujarat), by South (Andhra Pradesh, Tamil Nadu, Telangana, Karnataka, Kerala), by East (Bihar, West Bengal, Odisha, Jharkhand), by Central (Madhya Pradesh, Chhattisgarh) Forecast 2026-2034
Indonesia fertilizer industry market at USD 2.3 Billion in 2026, projected to reach USD 2.9 Billion by 2034, growing at a 2.57% CAGR.
Nov 2026|196 pages
$2900.00
Global agricultural PPE market valued at $4.8B in 2025, growing at 7.1% CAGR to $8.2B by 2033. Asia-Pacific leads with 42% share; Latin America fastest at 9.2%.
Nov 2026|190 pages
$2900.00
Global forestry mulching service market at $506 Million in 2025, CAGR 6.4% to 2032. Analysis of growth challenges, equipment costs, and regional dynamics.
Executive Overview: India's Tractor Market at an Inflection Point
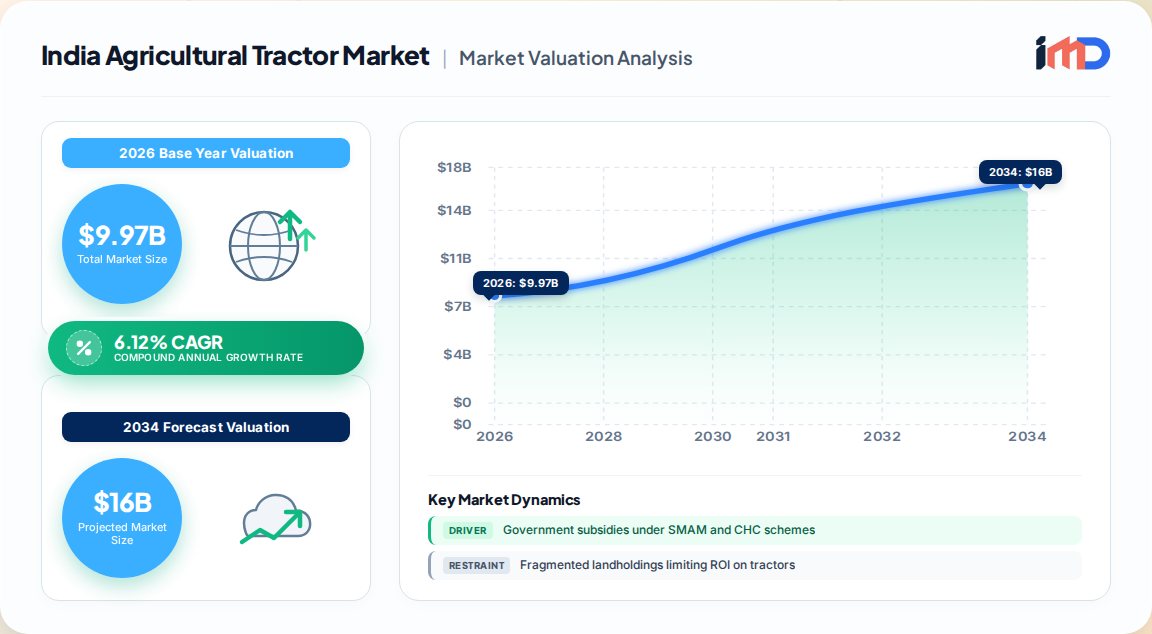
The India agricultural tractor market is the world's largest by unit volume, excluding China's sub-20 HP belt-driven segment, and accounts for approximately one-third of global tractor production. Our proprietary primary research estimates the market at USD 9.97 billion in 2026, rising from USD 9.39 billion in 2025, and projects it to reach USD 16.80 billion by 2034 at a CAGR of 6.12%. This growth is underpinned by deep structural drivers: tractor density stands at just 16 units per 1,000 hectares against 60+ in developed economies, signaling substantial headroom for penetration-led expansion.
India Agricultural Tractor Market Market Size (In Billion)
15.0B
10.0B
5.0B
0
9.395 B
2025
9.970 B
2026
10.58 B
2027
11.23 B
2028
11.91 B
2029
12.64 B
2030
13.42 B
2031
Metric
2025
2026
2034 Forecast
CAGR (2026–2034)
Market Size (USD Billion)
9.39
9.97
16.80
6.12%
Tractor Density (units/1,000 ha)
~16
~17
~26
–
Mechanization Rate (%)
~47
~49
~65
–
The market is transitioning from a volume-led replacement cycle to a value-driven upgrade cycle, where precision-ready implements, telematics bundling, and alternative fuel powertrains command premium pricing.
Key Market Drivers and Restraints
Drivers:
Government subsidy architecture: The Sub-Mission on Agricultural Mechanization (SMAM) covers 40–50% of equipment cost for individual buyers and up to 80% for Custom Hiring Centers (CHCs). Over 26,662 CHCs were established by December 2024, democratizing access to mechanization for marginal farmers.
Labor scarcity and wage inflation: With 70–80% of marginal and small farmers lacking tractors or power tillers, mechanical tillage via CHC rental (INR 800–1,200 per hectare) is 60–70% cheaper than manual labor (INR 3,000–4,000 over two days).
Precision agriculture adoption: OEMs are bundling telematics-ready rotavators; daily active usage of connected assets exceeds 85%, shortening payback periods for CHC investors.
Horticulture expansion: India's horticulture sector covered 28.98 million hectares in 2023-24, producing 353.19 million metric tons, driving demand for low-profile PTO sprayers.
Restraints:
Fragmented landholdings: Over 86% of Indian farmers hold less than 2 hectares, limiting individual ROI on full-priced tractors.
High upfront cost of powered implements: Restrains adoption in eastern and northeastern states.
Emission regulation compliance: The TREM-V emission rule (2026) requires PTO-power-matching retrofits, increasing costs, particularly for high-HP equipment.
Segmentation Analysis: Power Output, Drive Type, and Application
The market is segmented by power output, drive type, application, and engine type, with clear dominance patterns.
Segment
Sub-Segment
Market Share (2025)
Growth Outlook
Power Output
40–100 HP
55.2%
Dominant; optimal for diverse crops
Power Output
Less than 40 HP
51.11%*
Largest by revenue; horticulture-led
Power Output
Above 100 HP
~8%
Fastest CAGR ~7.8%
Drive Type
2-Wheel Drive
72.3%
Cost-affordable; flat terrain suitability
Drive Type
4-Wheel Drive
~27.7%
Fastest CAGR ~7.5%
Application
Plowing & Cultivating
41.35%
Largest machinery type
Application
Sprayers
–
Fastest CAGR 14.2%
Engine Type
Internal Combustion
~99%
Dominant; EV emerging
Engine Type
Electric
<1%
Fastest-growing from low base
Note: Less than 40 HP leads by revenue share in some segmentations, reflecting mini-tractor demand.
The 40–100 HP band is favored for its balance of power, versatility, and fuel efficiency across paddy, wheat, sugarcane, and cotton systems. The 2WD segment's dominance reflects affordability and compatibility with India's largely flat agricultural terrain. Above-100 HP and 4WD categories are gaining traction from commercial farming consolidation and construction demand.
Regional Outlook: Uttar Pradesh Leads, South Outpaces
Uttar Pradesh anchors the regional landscape with an 18.5% share, driven by India's largest cultivated area (17.7 million hectares) and highest absolute number of farm households.
India Agricultural Tractor Market Regional Market Share
Loading chart...
Region
Share (2025)
Key Characteristics
Uttar Pradesh
18.5%
Largest cultivated area; PM-KISAN-linked purchasing power
Maharashtra
12.4%
Horticulture and vineyard concentration
Rajasthan
10.8%
Large arable land base
Punjab
8.7%
Highest per-unit mechanization intensity
Southern Region
~18%
Fastest-growing; Andhra Pradesh, Tamil Nadu, Telangana
Eastern Region
~12%
Strong volume growth on low base
The southern region has consistently outpaced other regions, led by robust demand in Andhra Pradesh, Tamil Nadu, and Telangana. The eastern region reports strong growth from a low base, benefiting from government mechanization initiatives. Punjab exhibits the highest mechanization intensity, with the paddy-wheat rotation driving high fleet utilization.
Competitive Landscape and Strategic Developments
The market is characterized by medium concentration, with domestic OEMs dominating and international players holding niche positions. Key players include Mahindra & Mahindra Ltd. (market leader), Escorts Kubota Limited, Tractors and Farm Equipment Limited (TAFE), Sonalika (International Tractors Ltd.), Deere & Company, CNH Industrial, and AGCO Corporation.
Recent strategic developments:
Mahindra & Mahindra launched the Krish-e Smart Kit (INR 4,995 / USD 60), converting rotavators into connected assets with daily active usage exceeding 85%.
TAFE processed over 100,000 rental orders through its JFarm Services platform by January 2025.
CNH Industrial introduced AI-enabled sprayers under Case IH, New Holland, and Miller brands in June 2025, using camera sensing for green-on-brown weed detection.
Escorts Kubota and New Holland are investing in electric tractor R&D, supported by government PLI incentives.
OEMs are bundling telematics-ready implements and digital marketplaces, shortening payback periods for CHC investors and providing real-time maintenance data to service networks.
Value Chain and Supply Dynamics
The tractor value chain spans raw material suppliers (steel, castings), engine and powertrain manufacturers, OEM assembly plants, a 7,000-plus authorized dealer network, institutional financiers (NABARD, cooperative banks), and end-use buyers.
Value Chain Stage
Key Participants
Value Addition
Raw Materials
Steel, casting, rubber suppliers
~25% of production cost
Component Manufacturing
Engine, transmission, hydraulics
~35% of production cost
OEM Assembly
Mahindra, Escorts, TAFE, Sonalika, Deere
~25% of production cost
Distribution & Finance
7,000+ dealers, NABARD, banks
~10% of final price
End-Use
Farmers, CHCs, contractors
–
NABARD's agricultural credit target crossed INR 20 trillion in FY2024–25, expanding tractor loan eligibility and reducing down-payment barriers. The government's FARMS mobile app, launched in May 2024, digitizes CHC booking and connects farmers to over 26,000 service providers.
Strategic White-Space and Investment Opportunities
Custom Hiring Center expansion: With over 25,000 CHCs supported under the Farm Machinery Banks scheme, pooled ownership models extend market reach to sub-2-hectare farmers without requiring individual ownership.
Electric and alternative fuel tractors: PLI incentives for EV agricultural equipment are catalyzing R&D investment, creating a new high-value EV tractor segment.
Precision agriculture ecosystem: Telematics, GPS-enabled tractors, and data analytics platforms represent a high-growth adjacenta, with the smart tractor market projected to expand significantly.
Implements-as-a-service: Start-ups matching idle tractors with neighboring growers are expanding addressable demand beyond traditional dealer territories, with early uptake in Karnataka, Tamil Nadu, Madhya Pradesh, and Rajasthan.
The India agricultural tractor market is poised for sustained growth, transitioning from volume-led replacement to value-driven upgrades, with precision agriculture and alternative fuels shaping the next decade.
India Agricultural Tractor Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
India Agricultural Tractor Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2026
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 6.12% from 2020-2034
Segmentation
By Power Output
Less than 40 HP
40-100 HP
Above 100 HP
By Drive Type
2-Wheel Drive
Table of Contents
1. India Agricultural Tractor Market Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. India Agricultural Tractor Market Executive Summary
2.1. Market Snapshot
3. India Agricultural Tractor Market Dynamics
3.1. Market Drivers
3.1.1. Government subsidies under SMAM and CHC schemes
3.2.1. Precision agriculture and GPS-enabled tractor adoption
3.2.2. Telematics-ready implement bundling by OEMs
3.2.3. Electric and alternative fuel tractor development
3.2.4. Implements-as-a-service mobile platforms
3.2.5. Custom Hiring Center expansion
3.3. Market Restraints
3.3.1. Fragmented landholdings limiting ROI on tractors
3.3.2. High upfront cost of powered implements
3.3.3. TREM-V emission compliance costs
3.3.4. Monsoon dependency and seasonal demand volatility
3.4. Market Challenges
3.4.1. Shortage of skilled mechanics in Tier-3 towns
4-Wheel Drive
By Application
Plowing and Cultivating
Planting
Haying and Forage
Sprayers
Harvesting
Hauling
Row Crop
By Engine Type
Internal Combustion Engine
Electric Engine
Hybrid Engine
By Geography
North
Uttar Pradesh
Punjab
Haryana
Rajasthan
West
Maharashtra
Gujarat
South
Andhra Pradesh
Tamil Nadu
Telangana
Karnataka
Kerala
East
Bihar
West Bengal
Odisha
Jharkhand
Central
Madhya Pradesh
Chhattisgarh
3.4.2. Weak monsoon impacting purchasing power
3.4.3. High competition intensity among domestic OEMs
3.4.4. Infrastructure constraints in eastern and northeastern regions
4. India Agricultural Tractor Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. IMD Analyst Note
5. India Agricultural Tractor Market Analysis, Insights and Forecast, 2020-2034
5.1. Analysis, Insights and Forecast - by Power Output
5.1.1. Less than 40 HP
5.1.2. 40-100 HP
5.1.3. Above 100 HP
5.2. Analysis, Insights and Forecast - by Drive Type
5.2.1. 2-Wheel Drive
5.2.2. 4-Wheel Drive
5.3. Analysis, Insights and Forecast - by Application
5.3.1. Plowing and Cultivating
5.3.2. Planting
5.3.3. Haying and Forage
5.3.4. Sprayers
5.3.5. Harvesting
5.3.6. Hauling
5.3.7. Row Crop
5.4. Analysis, Insights and Forecast - by Engine Type
5.4.1. Internal Combustion Engine
5.4.2. Electric Engine
5.4.3. Hybrid Engine
5.5. Analysis, Insights and Forecast - by Region
5.5.1. North
5.5.2. West
5.5.3. South
5.5.4. East
5.5.5. Central
6. India Agricultural Tractor Market North Analysis, Insights and Forecast, 2020-2034
6.1. Analysis, Insights and Forecast - by Power Output
6.1.1. Less than 40 HP
6.1.2. 40-100 HP
6.1.3. Above 100 HP
6.2. Analysis, Insights and Forecast - by Drive Type
6.2.1. 2-Wheel Drive
6.2.2. 4-Wheel Drive
6.3. Analysis, Insights and Forecast - by Application
6.3.1. Plowing and Cultivating
6.3.2. Planting
6.3.3. Haying and Forage
6.3.4. Sprayers
6.3.5. Harvesting
6.3.6. Hauling
6.3.7. Row Crop
6.4. Analysis, Insights and Forecast - by Engine Type
6.4.1. Internal Combustion Engine
6.4.2. Electric Engine
6.4.3. Hybrid Engine
7. India Agricultural Tractor Market West Analysis, Insights and Forecast, 2020-2034
7.1. Analysis, Insights and Forecast - by Power Output
7.1.1. Less than 40 HP
7.1.2. 40-100 HP
7.1.3. Above 100 HP
7.2. Analysis, Insights and Forecast - by Drive Type
7.2.1. 2-Wheel Drive
7.2.2. 4-Wheel Drive
7.3. Analysis, Insights and Forecast - by Application
7.3.1. Plowing and Cultivating
7.3.2. Planting
7.3.3. Haying and Forage
7.3.4. Sprayers
7.3.5. Harvesting
7.3.6. Hauling
7.3.7. Row Crop
7.4. Analysis, Insights and Forecast - by Engine Type
7.4.1. Internal Combustion Engine
7.4.2. Electric Engine
7.4.3. Hybrid Engine
8. India Agricultural Tractor Market South Analysis, Insights and Forecast, 2020-2034
8.1. Analysis, Insights and Forecast - by Power Output
8.1.1. Less than 40 HP
8.1.2. 40-100 HP
8.1.3. Above 100 HP
8.2. Analysis, Insights and Forecast - by Drive Type
8.2.1. 2-Wheel Drive
8.2.2. 4-Wheel Drive
8.3. Analysis, Insights and Forecast - by Application
8.3.1. Plowing and Cultivating
8.3.2. Planting
8.3.3. Haying and Forage
8.3.4. Sprayers
8.3.5. Harvesting
8.3.6. Hauling
8.3.7. Row Crop
8.4. Analysis, Insights and Forecast - by Engine Type
8.4.1. Internal Combustion Engine
8.4.2. Electric Engine
8.4.3. Hybrid Engine
9. India Agricultural Tractor Market East Analysis, Insights and Forecast, 2020-2034
9.1. Analysis, Insights and Forecast - by Power Output
9.1.1. Less than 40 HP
9.1.2. 40-100 HP
9.1.3. Above 100 HP
9.2. Analysis, Insights and Forecast - by Drive Type
9.2.1. 2-Wheel Drive
9.2.2. 4-Wheel Drive
9.3. Analysis, Insights and Forecast - by Application
9.3.1. Plowing and Cultivating
9.3.2. Planting
9.3.3. Haying and Forage
9.3.4. Sprayers
9.3.5. Harvesting
9.3.6. Hauling
9.3.7. Row Crop
9.4. Analysis, Insights and Forecast - by Engine Type
9.4.1. Internal Combustion Engine
9.4.2. Electric Engine
9.4.3. Hybrid Engine
10. India Agricultural Tractor Market Central Analysis, Insights and Forecast, 2020-2034
10.1. Analysis, Insights and Forecast - by Power Output
10.1.1. Less than 40 HP
10.1.2. 40-100 HP
10.1.3. Above 100 HP
10.2. Analysis, Insights and Forecast - by Drive Type
10.2.1. 2-Wheel Drive
10.2.2. 4-Wheel Drive
10.3. Analysis, Insights and Forecast - by Application
10.3.1. Plowing and Cultivating
10.3.2. Planting
10.3.3. Haying and Forage
10.3.4. Sprayers
10.3.5. Harvesting
10.3.6. Hauling
10.3.7. Row Crop
10.4. Analysis, Insights and Forecast - by Engine Type
10.4.1. Internal Combustion Engine
10.4.2. Electric Engine
10.4.3. Hybrid Engine
11. India Agricultural Tractor Market Competitive Analysis
11.1. Company Profiles
11.1.1. Mahindra & Mahindra Ltd.
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. Escorts Kubota Limited
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. Tractors and Farm Equipment Limited (TAFE)
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. Sonalika (International Tractors Ltd.)
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. Deere & Company
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. CNH Industrial N.V.
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. AGCO Corporation
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. Kubota Corporation
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. Yanmar Co. Ltd.
11.1.9.1. Company Overview
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.1.10. Indo Farm Equipment Limited
11.1.10.1. Company Overview
11.1.10.2. Products
11.1.10.3. Company Financials
11.1.10.4. SWOT Analysis
11.1.11. Action Construction Equipment Ltd.
11.1.11.1. Company Overview
11.1.11.2. Products
11.1.11.3. Company Financials
11.1.11.4. SWOT Analysis
11.1.12. Standard Corporation India Limited
11.1.12.1. Company Overview
11.1.12.2. Products
11.1.12.3. Company Financials
11.1.12.4. SWOT Analysis
11.1.13. Tirth Agro Technology (Shaktiman)
11.1.13.1. Company Overview
11.1.13.2. Products
11.1.13.3. Company Financials
11.1.13.4. SWOT Analysis
11.1.14. Beri Udyog Pvt. Ltd. (Fieldking)
11.1.14.1. Company Overview
11.1.14.2. Products
11.1.14.3. Company Financials
11.1.14.4. SWOT Analysis
11.1.15. Maschio Gaspardo S.p.A.
11.1.15.1. Company Overview
11.1.15.2. Products
11.1.15.3. Company Financials
11.1.15.4. SWOT Analysis
11.1.16. SDF Group
11.1.16.1. Company Overview
11.1.16.2. Products
11.1.16.3. Company Financials
11.1.16.4. SWOT Analysis
11.1.17. Deutz-Fahr
11.1.17.1. Company Overview
11.1.17.2. Products
11.1.17.3. Company Financials
11.1.17.4. SWOT Analysis
11.1.18. CLAAS
11.1.18.1. Company Overview
11.1.18.2. Products
11.1.18.3. Company Financials
11.1.18.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
List of Figures
Figure 1: Global India Agricultural Tractor Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North India Agricultural Tractor Market Revenue (Billion), by Power Output 2026 & 2034
Figure 3: North India Agricultural Tractor Market Revenue Share (%), by Power Output 2026 & 2034
Figure 4: North India Agricultural Tractor Market Revenue (Billion), by Drive Type 2026 & 2034
Figure 5: North India Agricultural Tractor Market Revenue Share (%), by Drive Type 2026 & 2034
Figure 6: North India Agricultural Tractor Market Revenue (Billion), by Application 2026 & 2034
Figure 7: North India Agricultural Tractor Market Revenue Share (%), by Application 2026 & 2034
Figure 8: North India Agricultural Tractor Market Revenue (Billion), by Engine Type 2026 & 2034
Figure 9: North India Agricultural Tractor Market Revenue Share (%), by Engine Type 2026 & 2034
Figure 10: North India Agricultural Tractor Market Revenue (Billion), by Country 2026 & 2034
Figure 11: North India Agricultural Tractor Market Revenue Share (%), by Country 2026 & 2034
Figure 12: West India Agricultural Tractor Market Revenue (Billion), by Power Output 2026 & 2034
Figure 13: West India Agricultural Tractor Market Revenue Share (%), by Power Output 2026 & 2034
Figure 14: West India Agricultural Tractor Market Revenue (Billion), by Drive Type 2026 & 2034
Figure 15: West India Agricultural Tractor Market Revenue Share (%), by Drive Type 2026 & 2034
Figure 16: West India Agricultural Tractor Market Revenue (Billion), by Application 2026 & 2034
Figure 17: West India Agricultural Tractor Market Revenue Share (%), by Application 2026 & 2034
Figure 18: West India Agricultural Tractor Market Revenue (Billion), by Engine Type 2026 & 2034
Figure 19: West India Agricultural Tractor Market Revenue Share (%), by Engine Type 2026 & 2034
Figure 20: West India Agricultural Tractor Market Revenue (Billion), by Country 2026 & 2034
Figure 21: West India Agricultural Tractor Market Revenue Share (%), by Country 2026 & 2034
Figure 22: South India Agricultural Tractor Market Revenue (Billion), by Power Output 2026 & 2034
Figure 23: South India Agricultural Tractor Market Revenue Share (%), by Power Output 2026 & 2034
Figure 24: South India Agricultural Tractor Market Revenue (Billion), by Drive Type 2026 & 2034
Figure 25: South India Agricultural Tractor Market Revenue Share (%), by Drive Type 2026 & 2034
Figure 26: South India Agricultural Tractor Market Revenue (Billion), by Application 2026 & 2034
Figure 27: South India Agricultural Tractor Market Revenue Share (%), by Application 2026 & 2034
Figure 28: South India Agricultural Tractor Market Revenue (Billion), by Engine Type 2026 & 2034
Figure 29: South India Agricultural Tractor Market Revenue Share (%), by Engine Type 2026 & 2034
Figure 30: South India Agricultural Tractor Market Revenue (Billion), by Country 2026 & 2034
Figure 31: South India Agricultural Tractor Market Revenue Share (%), by Country 2026 & 2034
Figure 32: East India Agricultural Tractor Market Revenue (Billion), by Power Output 2026 & 2034
Figure 33: East India Agricultural Tractor Market Revenue Share (%), by Power Output 2026 & 2034
Figure 34: East India Agricultural Tractor Market Revenue (Billion), by Drive Type 2026 & 2034
Figure 35: East India Agricultural Tractor Market Revenue Share (%), by Drive Type 2026 & 2034
Figure 36: East India Agricultural Tractor Market Revenue (Billion), by Application 2026 & 2034
Figure 37: East India Agricultural Tractor Market Revenue Share (%), by Application 2026 & 2034
Figure 38: East India Agricultural Tractor Market Revenue (Billion), by Engine Type 2026 & 2034
Figure 39: East India Agricultural Tractor Market Revenue Share (%), by Engine Type 2026 & 2034
Figure 40: East India Agricultural Tractor Market Revenue (Billion), by Country 2026 & 2034
Figure 41: East India Agricultural Tractor Market Revenue Share (%), by Country 2026 & 2034
Figure 42: Central India Agricultural Tractor Market Revenue (Billion), by Power Output 2026 & 2034
Figure 43: Central India Agricultural Tractor Market Revenue Share (%), by Power Output 2026 & 2034
Figure 44: Central India Agricultural Tractor Market Revenue (Billion), by Drive Type 2026 & 2034
Figure 45: Central India Agricultural Tractor Market Revenue Share (%), by Drive Type 2026 & 2034
Figure 46: Central India Agricultural Tractor Market Revenue (Billion), by Application 2026 & 2034
Figure 47: Central India Agricultural Tractor Market Revenue Share (%), by Application 2026 & 2034
Figure 48: Central India Agricultural Tractor Market Revenue (Billion), by Engine Type 2026 & 2034
Figure 49: Central India Agricultural Tractor Market Revenue Share (%), by Engine Type 2026 & 2034
Figure 50: Central India Agricultural Tractor Market Revenue (Billion), by Country 2026 & 2034
Figure 51: Central India Agricultural Tractor Market Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Global India Agricultural Tractor Market Revenue Billion Forecast, by Power Output 2020 & 2034
Table 2: Global India Agricultural Tractor Market Revenue Billion Forecast, by Drive Type 2020 & 2034
Table 3: Global India Agricultural Tractor Market Revenue Billion Forecast, by Application 2020 & 2034
Table 4: Global India Agricultural Tractor Market Revenue Billion Forecast, by Engine Type 2020 & 2034
Table 5: Global India Agricultural Tractor Market Revenue Billion Forecast, by Region 2020 & 2034
Table 6: North India Agricultural Tractor Market Revenue Billion Forecast, by Power Output 2020 & 2034
Table 7: North India Agricultural Tractor Market Revenue Billion Forecast, by Drive Type 2020 & 2034
Table 8: North India Agricultural Tractor Market Revenue Billion Forecast, by Application 2020 & 2034
Table 9: North India Agricultural Tractor Market Revenue Billion Forecast, by Engine Type 2020 & 2034
Table 10: North India Agricultural Tractor Market Revenue Billion Forecast, by Country 2020 & 2034
Table 11: Uttar Pradesh India Agricultural Tractor Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 12: Punjab India Agricultural Tractor Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 13: Haryana India Agricultural Tractor Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 14: Rajasthan India Agricultural Tractor Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 15: West India Agricultural Tractor Market Revenue Billion Forecast, by Power Output 2020 & 2034
Table 16: West India Agricultural Tractor Market Revenue Billion Forecast, by Drive Type 2020 & 2034
Table 17: West India Agricultural Tractor Market Revenue Billion Forecast, by Application 2020 & 2034
Table 18: West India Agricultural Tractor Market Revenue Billion Forecast, by Engine Type 2020 & 2034
Table 19: West India Agricultural Tractor Market Revenue Billion Forecast, by Country 2020 & 2034
Table 20: Maharashtra India Agricultural Tractor Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 21: Gujarat India Agricultural Tractor Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 22: South India Agricultural Tractor Market Revenue Billion Forecast, by Power Output 2020 & 2034
Table 23: South India Agricultural Tractor Market Revenue Billion Forecast, by Drive Type 2020 & 2034
Table 24: South India Agricultural Tractor Market Revenue Billion Forecast, by Application 2020 & 2034
Table 25: South India Agricultural Tractor Market Revenue Billion Forecast, by Engine Type 2020 & 2034
Table 26: South India Agricultural Tractor Market Revenue Billion Forecast, by Country 2020 & 2034
Table 27: Andhra Pradesh India Agricultural Tractor Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 28: Tamil Nadu India Agricultural Tractor Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 29: Telangana India Agricultural Tractor Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 30: Karnataka India Agricultural Tractor Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 31: Kerala India Agricultural Tractor Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 32: East India Agricultural Tractor Market Revenue Billion Forecast, by Power Output 2020 & 2034
Table 33: East India Agricultural Tractor Market Revenue Billion Forecast, by Drive Type 2020 & 2034
Table 34: East India Agricultural Tractor Market Revenue Billion Forecast, by Application 2020 & 2034
Table 35: East India Agricultural Tractor Market Revenue Billion Forecast, by Engine Type 2020 & 2034
Table 36: East India Agricultural Tractor Market Revenue Billion Forecast, by Country 2020 & 2034
Table 37: Bihar India Agricultural Tractor Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 38: West Bengal India Agricultural Tractor Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 39: Odisha India Agricultural Tractor Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 40: Jharkhand India Agricultural Tractor Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 41: Central India Agricultural Tractor Market Revenue Billion Forecast, by Power Output 2020 & 2034
Table 42: Central India Agricultural Tractor Market Revenue Billion Forecast, by Drive Type 2020 & 2034
Table 43: Central India Agricultural Tractor Market Revenue Billion Forecast, by Application 2020 & 2034
Table 44: Central India Agricultural Tractor Market Revenue Billion Forecast, by Engine Type 2020 & 2034
Table 45: Central India Agricultural Tractor Market Revenue Billion Forecast, by Country 2020 & 2034
Table 46: Madhya Pradesh India Agricultural Tractor Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 47: Chhattisgarh India Agricultural Tractor Market Revenue (Billion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1What is the current size of the India agricultural tractor market?
The India agricultural tractor market was valued at USD 9.97 billion in 2026, growing from USD 9.39 billion in 2025, and is projected to reach USD 16.80 billion by 2034 at a CAGR of 6.12%.
2Which power output segment dominates the India tractor market?
The 40–100 HP segment dominates with a 55.2% share in 2025, favored for its balance of power, versatility, and fuel efficiency across diverse cropping systems.
3Which region holds the largest share in the India tractor market?
Uttar Pradesh commands the largest regional share at 18.5% in 2025, driven by its 17.7 million hectares of cultivated area and highest number of farm households.
4What are the key growth drivers for the India agricultural tractor market?
Government subsidies under SMAM (40–50% of equipment cost), labor scarcity during Kharif sowing, precision agriculture adoption, and horticulture expansion are the primary drivers.
5Who are the major players in the India tractor market?
Major players include Mahindra & Mahindra Ltd., Escorts Kubota Limited, Tractors and Farm Equipment Limited (TAFE), Sonalika (International Tractors Ltd.), Deere & Company, and CNH Industrial.
Methodology
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
Conducted 70–80% primary research through structured interviews with senior executives across the agricultural tractor value chain, including OEM product managers, dealer network heads, CHC operators, and farm equipment financiers.
Interviewed 3–4 specific stakeholder groups: Procurement Directors at OEMs, Farm Machinery Dealers, Custom Hiring Center Owners, and Agricultural Credit Officers at NABARD and cooperative banks.
Surveyed 4–5 company types: Tractor OEMs, Implement Manufacturers, Component Suppliers (engines, transmissions, hydraulics), Distribution/Dealer Networks, and Financial Institutions.
Engaged with industry associations including the Tractor and Mechanization Association (TMA) and the Federation of Indian Chambers of Commerce & Industry (FICCI) for validation of production and sales data.
Primary interviews focused on qualitative insights on demand drivers, pricing trends, and technology adoption patterns.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Procurement Director
30%
Farm Machinery Dealer
25%
Custom Hiring Center Owner
25%
Agricultural Credit Officer
20%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Tractor OEMs
40%
Implement Manufacturers
25%
Component Suppliers
20%
Dealer Networks
10%
Financial Institutions
5%
Secondary Research & Industry Benchmarking
20–30% secondary research sourced from official government databases, industry trade associations, and financial databases.
Utilized Bloomberg, Factiva, Hoovers, and PitchBook for company financials, M&A activity, and competitive intelligence.
Cited official sources including the Ministry of Agriculture & Farmers Welfare (agriwelfare.gov.in), NABARD (nabard.org), PIB (pib.gov.in), and Tractor and Mechanization Association (tma.org.in) for production, sales, and policy data.
Benchmarked against FAO and World Bank agricultural mechanization indicators and UN Comtrade trade flows for tractor and implement segments.
All data triangulated to ensure consistency across supply-side (production, imports) and demand-side (sales, registrations) metrics.
Demand Modeling & Market Estimation
Employed top-down and bottom-up methodologies simultaneously, validated via multi-level data triangulation.
Bottom-up market sizing incorporated 3–4 specific quantitative metrics: tractor unit sales by state and HP band, average selling price (ASP) by segment, replacement demand cycles, and CHC-driven rental fleet additions.
Top-down modeling used GDP-agriculture correlation, mechanization rate projections, and government expenditure on farm mechanization.
Segment-level forecasts (by power output, drive type, application) were built using weighted growth indices derived from primary interviews and historical penetration curves.
Data Accuracy & Quality Check
Guaranteed estimated data accuracy level of 85–90% through rigorous validation protocols.
Multi-level data triangulation: cross-verification of OEM production data with dealer sales, import/export records, and government registration databases.
Every report is updated to the date of purchase, incorporating the latest available monthly production and sales data from industry associations.
Quality checks include outlier detection, consistency audits across segments, and peer review by senior analysts.
Data flagged where primary and secondary sources diverge by more than 5%, with resolution through expert re-interviews.