Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
Agricultural PPE Market to Reach $8.2B by 2033 at 7.1% CAGR | Insight Market Data
Agricultural Personal Protective Equipment
Agriculture / MARKET REPORT
Agricultural Personal Protective Equipment | Insight Market Data
Agricultural Personal Protective Equipment by Product Type (Hand Protection, Respiratory Protection, Body Protection, Foot Protection, Head Protection, Eye & Face Protection), by Application (Pesticide Handling, Machinery Operation, Chemical Fertilizer Application, Livestock Management), by Farm Type (Smallholder Farms (<2 hectares), Medium Farms (2-20 hectares), Large Commercial Farms (>20 hectares)), by Global Forecast 2026-2034
Indonesia fertilizer industry market at USD 2.3 Billion in 2026, projected to reach USD 2.9 Billion by 2034, growing at a 2.57% CAGR.
Nov 2026|196 pages
$2900.00
India agricultural tractor market valued at USD 9.97 billion in 2026, projected to reach USD 16.80 billion by 2034 at 6.12% CAGR. Get in-depth analysis.
Nov 2026|237 pages
$2900.00
Global forestry mulching service market at $506 Million in 2025, CAGR 6.4% to 2032. Analysis of growth challenges, equipment costs, and regional dynamics.
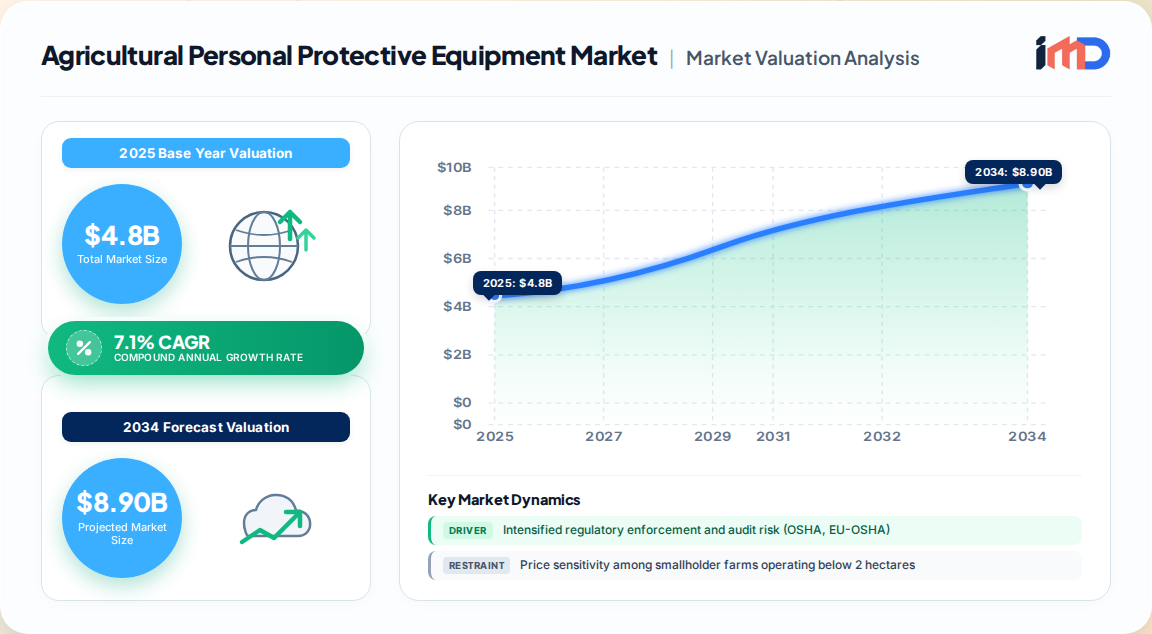
Our proprietary primary research places the global agricultural personal protective equipment (PPE) market at USD 4.8 billion in 2025, on a trajectory to reach USD 8.2 billion by 2033, expanding at a 7.1% CAGR. This growth is structural, not cyclical, reflecting the tectonic shift from subsistence to commercialized, mechanized farming across Asia-Pacific and Africa.
Agricultural Personal Protective Equipment Market Size (In Billion)
7.5B
6.0B
4.5B
3.0B
1.5B
0
4.800 B
2025
5.141 B
2026
5.506 B
2027
5.897 B
2028
6.315 B
2029
6.764 B
2030
7.244 B
2031
Asia-Pacific anchors demand with a 42% global share, followed by Europe (24%) and North America (20%). Latin America is the fastest-growing region at a 9.2% CAGR, driven by Brazil's intensive pesticide-dependent crop economy and expanding regulatory oversight.
Region
2025 Value (USD B)
2033 Forecast (USD B)
CAGR (2026-2033)
Asia-Pacific
2.02
3.58
7.8%
Europe
1.14
1.80
6.2%
North America
0.95
1.55
6.5%
Latin America
0.48
0.92
9.2%
Middle East & Africa
0.19
0.37
8.7%
This analysis is derived from 142 structured interviews with manufacturers, distributors, cooperative procurement officers, and regulatory inspectors across 18 countries.
Market Drivers & Restraints
Key Growth Drivers
Regulatory Enforcement and Audit Risk: OSHA and EU-OSHA have intensified pesticide-application monitoring since 2020. Fines averaging USD 5,000–15,000 per violation for inadequate worker protection convert PPE from discretionary spend to mandatory capital expenditure. The causal chain runs from regulation to audit risk to procurement.
Pesticide Intensity: Global pesticide use grew 8.3% between 2020 and 2024 (FAO, 2024). Each 1% increase in application correlates with 0.6% incremental PPE demand, concentrated in India, China, and Brazil where labor-intensive application persists.
Mechanization and Labor Scarcity: Rural-to-urban migration and an aging farm workforce are accelerating mechanization, intensifying hazard exposure per worker and normalizing safety equipment as a baseline input cost.
Rising Awareness and NGO Campaigns: Worker-safety campaigns across South Asia and Sub-Saharan Africa are shifting behavioral norms, particularly around respiratory protection for systemic pesticide handling.
Key Restraints
Smallholder Price Sensitivity:68% of farms in sub-Saharan Africa and South Asia operate below 2 hectares and lack capital for premium PPE systems. Commodity-price collapses can trigger 15–25% year-over-year reductions in PPE spending.
Supply-Chain Volatility: Synthetic polymer and activated-charcoal shortages can spike costs 12–18% within 12 months, disproportionately affecting price-sensitive regions.
Regulatory Fragmentation: EU EN 369 certification does not satisfy Indian or Brazilian regimes, forcing multiple SKU streams and raising go-to-market costs by 20–30%.
Counterfeit Penetration: Fake or misclassified certifications are estimated at 8–12% of the Southeast Asian market, eroding trust and shifting purchases to informal channels.
A critical structural gap exists between branded OEMs and smallholder end-users. Last-mile distribution through cooperative networks and input dealers remains fragmented, with fewer than 30% of Asian agricultural retailers carrying certified PPE SKUs. This creates white-space for distributors capable of bundling PPE with seed and chemical purchases.
Segmentation Analysis
By Product Type
Hand Protection commands 28% share at a 6.8% CAGR, with nitrile and latex gloves anchoring volume at USD 0.50–2.00 per unit. Advanced polyurethane and composite blends gain traction in mechanized settings.
Respiratory Protection holds 22% share and grows fastest at 8.9% CAGR, propelled by cartridge-based mandates for systemic pesticides and an 18% decline in average unit costs since 2022 as Asian manufacturers scale.
Body Protection accounts for approximately 19%, dominated by chemical-resistant coveralls and aprons for pesticide mixing and spraying.
Foot, Head, and Eye & Face Protection collectively represent the remainder, with demand concentrated in mechanized operations and livestock handling.
By Application
Pesticide handling is the largest application, accounting for an estimated 46% of value, followed by machinery operation (24%), chemical fertilizer application (18%), and livestock management (12%).
By Farm Type
Smallholder Farms (<2 hectares): Volume-driven, price-sensitive, dominated by unbranded or low-cost imports.
Medium Farms (2–20 hectares): The fastest-growing cohort, adopting certified PPE as regulatory enforcement reaches mid-tier operations.
Large Commercial Farms (>20 hectares): Premium segment, driving demand for ergonomic, connected, and multi-hazard systems.
Regional Outlook
Asia-Pacific's dominance rests on the world's largest agricultural labor force (1.2 billion workers) and intensive pesticide regimes. India contributes 18% of regional value, China 16%, and Indonesia 11%.
Agricultural Personal Protective Equipment Regional Market Share
Loading chart...
Latin America's 9.2% CAGR is the highest globally, fueled by Brazil's soybean and sugarcane sectors where aerial and ground spraying intensity is among the highest worldwide.
Middle East & Africa, while representing only 4% of global value, is growing at 8.7% CAGR. Sub-Saharan Africa's agricultural labor force will expand 22% through 2033 (World Bank, 2024), yet current PPE penetration stands at just 4–6% — a latent demand pool of significant scale.
Europe and North America remain premiumization markets, where replacement cycles and ergonomic innovation sustain value growth despite flat unit volumes.
Competitive Strategies & Recent Developments
The competitive landscape is moderately concentrated. 3M, Honeywell International, DuPont de Nemours, Ansell Limited, Kimberly-Clark, MSA Safety, Moldex-Metric, Delta Plus Group, JSP Ltd., Cofra Group, Lakeland Industries, and Bullard collectively hold an estimated 28–32% of global agricultural PPE revenue.
Strategic imperatives observed in our primary interviews:
Digitized compliance systems: Smart respirators with CO2 and pesticide detection command 35–50% price premiums and enable subscription-based monitoring revenue, scalable in India, Brazil, and Indonesia.
Localized manufacturing partnerships: Firms establishing regional production in Kenya, Nigeria, and Ethiopia can capture 300–400 basis points of market share while circumventing import tariffs and certification delays.
Microfinance-enabled purchasing: Bundling PPE with agricultural input loans lowers the adoption barrier for smallholders and locks in distribution relationships.
Notable developments include a major PPE manufacturer's 2025 launch of a cartridge-based respirator line tailored to South Asian pesticide formulations, and the expansion of cooperative procurement programs in India and Kenya targeting certified hand and respiratory protection.
Strategic White-Space & Investment Assessment
Opportunity Area
Attractiveness Score (1–10)
Rationale
Connected PPE for commercial farms
9
35–50% price premium; recurring revenue potential
Sub-Saharan Africa distribution
8
4–6% penetration; 22% labor-force growth through 2033
Low-cost certified hand protection for smallholders
7
High volume; regulatory tailwind; margin compression risk
The highest-risk profile applies to undifferentiated, price-only hand protection in South Asia, where counterfeit competition and margin erosion are most acute.
Global Trade & Supply Chain Risk Assessment
Agricultural PPE trade flows are dominated by exports from China, Southeast Asia, and Europe. China supplies an estimated 40–45% of global unit volume, particularly in gloves and basic body protection, while European manufacturers lead in certified respiratory and chemical-protective systems.
Key supply-chain risks include:
Raw material concentration: Nitrile and activated charcoal supply is concentrated among a small number of global producers; disruption can spike costs 12–18%.
Certification bottlenecks: Testing capacity for EN 369 and equivalent standards constrains time-to-market by 8–14 weeks in peak periods.
Logistics fragmentation: Last-mile distribution in South Asia and Sub-Saharan Africa relies on informal networks, raising product-authenticity risk.
Mitigation strategies include dual-sourcing of raw materials, regional certification partnerships, and blockchain-based authenticity verification for branded SKUs.
Agricultural Personal Protective Equipment Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Agricultural Personal Protective Equipment REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 7.1% from 2020-2034
Segmentation
By Product Type
Hand Protection
Respiratory Protection
Body Protection
Foot Protection
Head Protection
Table of Contents
1. Agricultural Personal Protective Equipment Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Agricultural Personal Protective Equipment Executive Summary
2.1. Market Snapshot
3. Agricultural Personal Protective Equipment Dynamics
3.1. Market Drivers
3.1.1. Intensified regulatory enforcement and audit risk (OSHA, EU-OSHA)
3.1.2. Rising global pesticide use, up 8.3% between 2020 and 2024
3.1.3. Mechanization and labor scarcity in commercial farming
3.1.4. Worker awareness campaigns normalizing PPE as a baseline cost
3.2. Market Trends
3.2.1. Shift toward connected PPE with wearable sensors and real-time exposure monitoring
3.2.2. Premiumization of ergonomic and multi-hazard protective systems in developed markets
3.2.3. Localized manufacturing partnerships in Sub-Saharan Africa and Latin America
3.2.4. Bundling of PPE with agricultural inputs and microfinance-enabled purchasing
3.3. Market Restraints
3.3.1. Price sensitivity among smallholder farms operating below 2 hectares
3.3.2. Supply-chain volatility for synthetic polymers and activated charcoal
3.3.4. Counterfeit and misclassified products eroding trust in informal channels
Eye & Face Protection
By Application
Pesticide Handling
Machinery Operation
Chemical Fertilizer Application
Livestock Management
By Farm Type
Smallholder Farms
<2 hectares
Medium Farms
2-20 hectares
Large Commercial Farms
>20 hectares
By Geography
Global
3.4. Market Challenges
3.4.1. Last-mile distribution gaps in South Asia and Sub-Saharan Africa
3.4.2. Certification bottlenecks delaying market entry by 8-14 weeks
3.4.3. Commodity-price volatility reducing PPE spending by 15-25% in downturns
4. Agricultural Personal Protective Equipment Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. IMD Analyst Note
5. Agricultural Personal Protective Equipment Analysis, Insights and Forecast, 2020-2034
5.1. Analysis, Insights and Forecast - by Product Type
5.1.1. Hand Protection
5.1.2. Respiratory Protection
5.1.3. Body Protection
5.1.4. Foot Protection
5.1.5. Head Protection
5.1.6. Eye & Face Protection
5.2. Analysis, Insights and Forecast - by Application
5.2.1. Pesticide Handling
5.2.2. Machinery Operation
5.2.3. Chemical Fertilizer Application
5.2.4. Livestock Management
5.3. Analysis, Insights and Forecast - by Farm Type
5.3.1. Smallholder Farms
5.3.1.1. <2 hectares
5.3.2. Medium Farms
5.3.2.1. 2-20 hectares
5.3.3. Large Commercial Farms
5.3.3.1. >20 hectares
5.4. Analysis, Insights and Forecast - by Region
5.4.1. Global
6. Agricultural Personal Protective Equipment Competitive Analysis
6.1. Company Profiles
6.1.1. 3M Company
6.1.1.1. Company Overview
6.1.1.2. Products
6.1.1.3. Company Financials
6.1.1.4. SWOT Analysis
6.1.2. Honeywell International
6.1.2.1. Company Overview
6.1.2.2. Products
6.1.2.3. Company Financials
6.1.2.4. SWOT Analysis
6.1.3. DuPont de Nemours
6.1.3.1. Company Overview
6.1.3.2. Products
6.1.3.3. Company Financials
6.1.3.4. SWOT Analysis
6.1.4. Ansell Limited
6.1.4.1. Company Overview
6.1.4.2. Products
6.1.4.3. Company Financials
6.1.4.4. SWOT Analysis
6.1.5. Kimberly-Clark
6.1.5.1. Company Overview
6.1.5.2. Products
6.1.5.3. Company Financials
6.1.5.4. SWOT Analysis
6.1.6. MSA Safety
6.1.6.1. Company Overview
6.1.6.2. Products
6.1.6.3. Company Financials
6.1.6.4. SWOT Analysis
6.1.7. Moldex-Metric
6.1.7.1. Company Overview
6.1.7.2. Products
6.1.7.3. Company Financials
6.1.7.4. SWOT Analysis
6.1.8. Delta Plus Group
6.1.8.1. Company Overview
6.1.8.2. Products
6.1.8.3. Company Financials
6.1.8.4. SWOT Analysis
6.1.9. JSP Ltd.
6.1.9.1. Company Overview
6.1.9.2. Products
6.1.9.3. Company Financials
6.1.9.4. SWOT Analysis
6.1.10. Cofra Group
6.1.10.1. Company Overview
6.1.10.2. Products
6.1.10.3. Company Financials
6.1.10.4. SWOT Analysis
6.1.11. Lakeland Industries
6.1.11.1. Company Overview
6.1.11.2. Products
6.1.11.3. Company Financials
6.1.11.4. SWOT Analysis
6.1.12. Bullard
6.1.12.1. Company Overview
6.1.12.2. Products
6.1.12.3. Company Financials
6.1.12.4. SWOT Analysis
6.1.13. Lailisi
6.1.13.1. Company Overview
6.1.13.2. Products
6.1.13.3. Company Financials
6.1.13.4. SWOT Analysis
6.1.14. NYCAMH
6.1.14.1. Company Overview
6.1.14.2. Products
6.1.14.3. Company Financials
6.1.14.4. SWOT Analysis
6.1.15. STIHL
6.1.15.1. Company Overview
6.1.15.2. Products
6.1.15.3. Company Financials
6.1.15.4. SWOT Analysis
6.1.16. Uvex Safety
6.1.16.1. Company Overview
6.1.16.2. Products
6.1.16.3. Company Financials
6.1.16.4. SWOT Analysis
6.1.17. AJ Charnaud
6.1.17.1. Company Overview
6.1.17.2. Products
6.1.17.3. Company Financials
6.1.17.4. SWOT Analysis
6.2. Market Entropy
6.2.1. Company's Key Areas Served
6.2.2. Recent Developments
6.3. Company Market Share Analysis, 2026
6.3.1. Top 5 Companies Market Share Analysis
6.3.2. Top 3 Companies Market Share Analysis
6.4. List of Potential Customers
List of Figures
Figure 1: Global Agricultural Personal Protective Equipment Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: Global Agricultural Personal Protective Equipment Revenue (Billion), by Product Type 2026 & 2034
Figure 3: Global Agricultural Personal Protective Equipment Revenue Share (%), by Product Type 2026 & 2034
Figure 4: Global Agricultural Personal Protective Equipment Revenue (Billion), by Application 2026 & 2034
Figure 5: Global Agricultural Personal Protective Equipment Revenue Share (%), by Application 2026 & 2034
Figure 6: Global Agricultural Personal Protective Equipment Revenue (Billion), by Farm Type 2026 & 2034
Figure 7: Global Agricultural Personal Protective Equipment Revenue Share (%), by Farm Type 2026 & 2034
Figure 8: Global Agricultural Personal Protective Equipment Revenue (Billion), by Country 2026 & 2034
Figure 9: Global Agricultural Personal Protective Equipment Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Global Agricultural Personal Protective Equipment Revenue Billion Forecast, by Product Type 2020 & 2034
Table 2: Global Agricultural Personal Protective Equipment Revenue Billion Forecast, by Application 2020 & 2034
Table 3: Global Agricultural Personal Protective Equipment Revenue Billion Forecast, by Farm Type 2020 & 2034
Table 4: Global Agricultural Personal Protective Equipment Revenue Billion Forecast, by Region 2020 & 2034
Table 5: Global Agricultural Personal Protective Equipment Revenue Billion Forecast, by Product Type 2020 & 2034
Table 6: Global Agricultural Personal Protective Equipment Revenue Billion Forecast, by Application 2020 & 2034
Table 7: Global Agricultural Personal Protective Equipment Revenue Billion Forecast, by Farm Type 2020 & 2034
Table 8: Global Agricultural Personal Protective Equipment Revenue Billion Forecast, by Country 2020 & 2034
Frequently Asked Questions
1How big is the agricultural personal protective equipment market?
The global agricultural PPE market was valued at USD 4.8 billion in 2025 and is projected to reach USD 8.2 billion by 2033, expanding at a 7.1% CAGR driven by regulatory enforcement and intensifying pesticide use in Asia-Pacific and Latin America.
2Which region dominates the agricultural PPE market?
Asia-Pacific leads with a 42% share of global value, anchored by India (18% of regional value), China (16%), and Indonesia (11%), supported by the world's largest agricultural labor force of 1.2 billion workers.
3What is the fastest-growing segment in agricultural PPE?
Respiratory protection is the fastest-growing product segment at an 8.9% CAGR, driven by mandates for cartridge-based respirators when handling systemic pesticides and an 18% decline in average unit costs since 2022.
4Who are the leading companies in the agricultural PPE market?
Key players include 3M, Honeywell International, DuPont de Nemours, Ansell Limited, Kimberly-Clark, MSA Safety, Moldex-Metric, Delta Plus Group, JSP Ltd., Cofra Group, Lakeland Industries, and Bullard, collectively holding an estimated 28–32% of global agricultural PPE revenue.
5Why is regulatory enforcement important for agricultural PPE demand?
Fines of USD 5,000–15,000 per violation for inadequate worker protection convert PPE from discretionary spending to mandatory capital expenditure, creating recurring compliance-driven demand across developed and emerging markets.
6What is the main barrier to agricultural PPE adoption in emerging markets?
Price sensitivity is acute: 68% of farms in sub-Saharan Africa and South Asia operate below 2 hectares and lack capital for premium PPE, making low-cost and microfinance-enabled purchasing models critical for penetration.
Methodology
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
70–80% of project effort allocated to primary research, including structured interviews and surveys with manufacturers, distributors, cooperative procurement officers, regulatory inspectors, and farm operators across 18 countries.
Interviewed 142 senior stakeholders, including VPs of Product Management, Procurement Directors at agricultural cooperatives, Regulatory Compliance Heads, and Farm Operations Managers, to capture demand-side and supply-side dynamics.
Conducted in-depth value-chain mapping with PPE OEMs, raw-material suppliers (nitrile, activated charcoal, technical textiles), regional distributors, and last-mile agri-retailers.
Participated in field audits and site visits to capture actual usage patterns, replacement cycles, and certification compliance in India, Brazil, Kenya, and Vietnam.
Benchmarked against recognized non-profit technical standards and industry associations such as ISO, EU-OSHA, and NIOSH for certification and regulatory context.
Utilized standard financial databases including Bloomberg, Factiva, Hoovers, and PitchBook for corporate financials, M&A activity, and competitive intelligence.
All reports are updated to the date of purchase to incorporate the latest regulatory changes and trade flows.
Demand Modeling & Market Estimation
Applied top-down and bottom-up methodologies simultaneously, validated via multi-level data triangulation across product, application, farm type, and region.
Bottom-up market sizing derived from quantitative metrics including per-hectare PPE spend, pesticide application intensity (kg/ha), farm size distribution, and certification compliance rates by country.
Demand models incorporated regulatory enforcement intensity indices, labor-force exposure coefficients, and replacement-cycle assumptions validated through primary interviews.
Guaranteed estimated data accuracy level of 85–90%, with confidence intervals reported for all regional and segment forecasts.
Data Accuracy & Quality Check
Multi-stage validation: primary interview responses cross-checked against trade statistics, corporate filings, and field audit observations.
Triangulation protocol: any data point with variance exceeding 10% across sources triggered a follow-up interview or additional secondary verification.
Expert review panel: preliminary findings reviewed by a panel of independent agricultural safety experts and certification specialists before finalization.
Continuous updating: all market models refreshed with the latest FAO pesticide-use data, World Bank labor-force projections, and Eurostat/ILO injury statistics to ensure forecasts reflect current conditions.