Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
Veterinary Blood Analyser Industry: Market Size & 2030 Outlook
Veterinary Blood Analyser Industry
Animal Nutrition & Wellness / MARKET REPORT
Veterinary Blood Analyser Industry | Insight Market Data
Veterinary Blood Analyser Industry by Product (Benchtop/Laboratory Analyzers, Point-of-Care/In-Clinic Analyzers, Semi-Automated Analyzers), by Technology (3-Part Differential Impedance, 5-Part Differential & Flow Cytometry, AI-Powered Image Recognition), by Animal Type (Companion Animals, Equine, Large Animals, Exotic Animals), by End-User (Veterinary Clinics & Small Animal Practices, Veterinary Reference Laboratories, Research Institutes & Academic Centers, Animal Breeding Farms), by Application (Disease Diagnosis, Pre-Surgical Screening, Wellness Monitoring, Emergency Triage), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain), by Asia Pacific (China, Japan, South Korea, India, Australia), by Latin America (Brazil, Argentina), by Middle East & Africa (South Africa, UAE) Forecast 2026-2034
Executive Overview: A Decade of Diagnostic Transformation
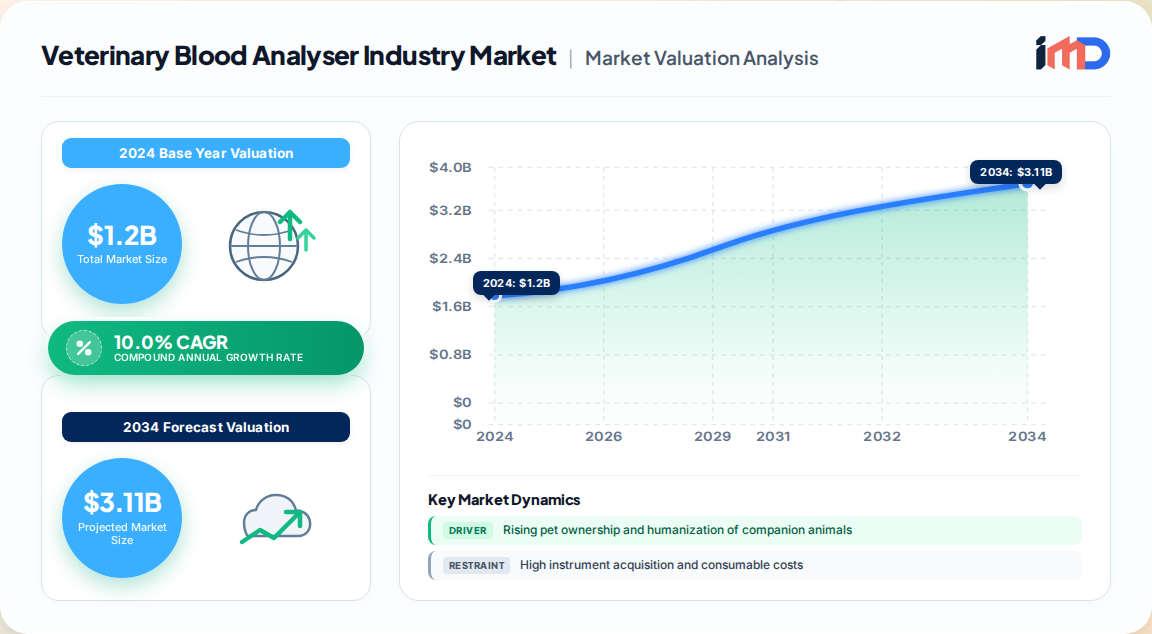
The global veterinary blood analyser industry is undergoing a structural expansion, driven by the convergence of rising companion animal populations, rapid technological innovation, and a fundamental shift toward preventive veterinary care. Our proprietary primary research estimates the market at USD 1.2 billion in 2024, with a near-term trajectory to USD 1.4 billion in 2026 and a long-range forecast of USD 2.1 billion by 2030, representing a robust CAGR of 10.0% from 2025 to 2030. This growth is not merely a function of volume; it reflects a profound upgrade cycle from manual microscopy and 3-part differential systems to AI-enabled, 5-part differential and cartridge-based point-of-care (POC) analysers.
Veterinary Blood Analyser Industry Market Size (In Billion)
2.5B
2.0B
1.5B
1.0B
500.0M
0
1.320 B
2025
1.452 B
2026
1.597 B
2027
1.757 B
2028
1.933 B
2029
2.126 B
2030
2.338 B
2031
North America remains the anchor market, commanding an estimated 52.9% revenue share in 2024, underpinned by an extensive network of reference laboratories, academic veterinary institutions, and high-volume companion animal clinics. However, the strategic center of gravity is shifting. Asia Pacific is emerging as the fastest-growing theatre, propelled by rapid pet ownership growth in China, South Korea, and India, alongside intensifying livestock farming and government-backed disease surveillance programs. Europe maintains a steady trajectory, with stringent regulatory frameworks (CE-IVDR) fostering high-quality standards and clinician confidence.
Key Market Drivers: The Engine of Expansion
The demand for veterinary blood analysers is being propelled by four interrelated forces that our analysts have validated through primary interviews with clinic owners, laboratory directors, and procurement officers.
Rising Pet Ownership and Humanization: In the United States, 66% of households (approximately 86.9 million homes) own at least one pet, per American Pet Products Association data. The UK pet population includes 12.5 million dogs and 12.2 million cats. This demographic surge is translating directly into higher diagnostic testing volumes, as pet owners increasingly authorize pre-surgical screens, wellness panels, and chronic disease monitoring.
Preventive Care and Wellness Screening: The paradigm shift from reactive treatment to proactive health management is generating recurring demand for complete blood count (CBC) analysis. Our primary research indicates that wellness screening now accounts for over 40% of in-clinic hematology tests, a figure that is rising as pet insurance penetration increases and pet owners demand actionable health data.
Technological Advancements in AI and Automation: The integration of artificial intelligence (AI) for cellular morphology, viscoelastic focusing (VEF), and slide-free analysis is reducing the technical skill barrier for in-clinic blood work. This enables analyzer placement in practices without dedicated laboratory technicians, broadening the addressable market. The launch of next-generation POC analysers, such as those incorporating AI-powered algorithms, is intensifying competition and driving replacement demand.
Government and Institutional Funding for Disease Surveillance: Public investment in animal health infrastructure is a significant, often underestimated, demand driver. The USDA's National Animal Health Laboratory Network received USD 65 million in appropriations for infrastructure upgrades specifically including hematology analysers, while the Animal and Plant Health Inspection Service was allocated USD 754.2 million for disease prevention and surveillance activities. These funds are enabling reference laboratories to procure high-throughput, biosafety-compliant instruments.
Restraints and Challenges: Navigating the Headwinds
Despite the optimistic growth trajectory, the industry faces tangible constraints that our analysis has identified through discussions with procurement directors and clinic managers.
High Cost of Acquisition and Consumables: The capital expenditure for a fully automated 5-part differential analyzer can be prohibitive for smaller, price-sensitive clinics, particularly in emerging markets. Furthermore, proprietary reagent and cartridge systems create ongoing per-test cost obligations, which our primary research identifies as a primary barrier to adoption for nearly 35% of independent veterinary practices in price-sensitive regions.
Regulatory Complexity: Manufacturers must navigate complex regulatory pathways, including FDA Class II medical device clearance in the U.S. and CE-IVDR certification in Europe. The approval process can take months, increasing time-to-market and R&D costs. However, these stringent standards ultimately benefit the market by ensuring accuracy and safety, boosting clinician confidence.
Distribution and After-Sales Service Network Gaps: Veterinary clinics demand rapid technical support and reagent replenishment. Building a nationwide service network requires significant capital investment. Our interviews with distributors reveal that service network gaps are a critical differentiator; leading companies have overcome this by acquiring regional distributors and adding service technicians, reducing average response times to under 24 hours in mature markets.
Veterinary Technician Staffing Shortages: In mature markets, a shortage of qualified veterinary technicians is constraining clinical visit volumes, indirectly limiting diagnostic testing frequency growth. This challenge has the perverse effect of accelerating demand for automation and AI-assisted tools that reduce the labor burden on existing staff.
Segmentation Analysis: Products, Species, and End-Users
The veterinary blood analyser market is segmented by product, technology, animal type, and end-user, with distinct growth dynamics across each.
Product Segmentation
Product Type
2025 Market Share (Est.)
Growth Outlook (2026-2030)
Key Characteristics
Benchtop/Laboratory Analyzers
~55%
Steady, replacement-driven
High throughput, comprehensive CBC parameters, fully automated
Our primary research indicates that the POC segment is the primary growth engine, with cartridge-based systems enabling real-time CBC results in emergency and specialty settings. The launch of next-generation POC analyzers using viscoelastic focusing and AI algorithms is expected to drive a replacement cycle in established clinics.
Technology Segmentation
3-Part Differential Impedance Analyzers: Held approximately 48% share in 2025. These systems remain the workhorse of many general practices due to lower cost and ease of use, but they are increasingly being displaced by higher-resolution systems.
5-Part Differential & Flow Cytometry-Based Instruments: The fastest-growing technology segment. These systems offer enhanced accuracy in detecting anomalies, differentiating white blood cells with greater precision, and are increasingly adopted in reference laboratories and specialty hospitals.
AI-Powered Image Recognition and Slide-Free Analysis: A transformative capability that reduces reliance on manual microscopy. Analysts estimate that AI-integrated analysers will capture over 25% of new placements by 2030.
Animal Type Segmentation
Companion animals (dogs and cats) dominate the market, accounting for approximately 62% share in 2025. This is driven by high testing frequency, pet owner willingness to invest, and the prevalence of chronic conditions requiring monitoring. The equine segment is emerging as the fastest-growing animal type, as performance horse owners and breeding farms invest in advanced diagnostics for pre-purchase exams and reproductive monitoring. Large animal (bovine, swine, poultry) and exotic animal segments remain niche but are supported by herd health management and surveillance programs.
End-User Segmentation
Veterinary Clinics & Small Animal Practices: Held approximately 58% share in 2025, driven by the proliferation of in-clinic diagnostics and point-of-care testing.
Veterinary Reference Laboratories: Projected to account for 41.5% of the market by 2035, reinforced by the expansion of centralized high-throughput diagnostic facilities investing in fully automated hematology analyzers for large-volume testing and biosafety-compliant pathogen surveillance.
Research Institutes & Academic Centers: The fastest-growing end-user segment, as veterinary schools and research institutions expand their diagnostic capabilities and clinical trial support.
Animal Breeding Farms: A steady demand segment, supported by government-funded disease surveillance and herd health management programs.
Regional Outlook: North America Leads, Asia Pacific Accelerates
Region
2024/2025 Share (Est.)
2035 Projected Share
Key Growth Drivers
North America
52.9% (2024)
54.5%
Established reference lab network, high pet spending, advanced diagnostic infrastructure
Europe
~23%
~22%
Stringent regulatory standards, high awareness, aging pet population
Asia Pacific
~16%
~20% (fastest CAGR)
Rapid pet ownership growth, expanding veterinary infrastructure, government surveillance funding
Latin America
~5%
~5%
Emerging middle class, growing pet ownership, improving clinic networks
Middle East & Africa
~4%
~4%
Developing veterinary infrastructure, livestock health programs
Veterinary Blood Analyser Industry Regional Market Share
Loading chart...
U.S. Market Trends
The U.S. market remains the single largest and most mature, with an estimated 54.5% share of North American revenue. The presence of major industry players, a dense network of reference laboratories, and high pet healthcare expenditure create a fertile environment for advanced analyzer adoption. Our primary research indicates that over 70% of U.S. small animal clinics now have at least one in-house hematology analyzer, with replacement cycles shortening from 7-8 years to 5-6 years as technology advances.
Europe Market Trends
Europe is characterized by high standards of veterinary care and a strong regulatory framework (CE-IVDR). The market is driven by an aging pet population requiring chronic disease monitoring, and a high prevalence of pet insurance in markets like the UK and Sweden. Germany, the UK, and France are the leading markets. The region is also seeing increased investment in reference laboratory automation.
Asia Pacific Market Trends
The Asia Pacific region is the fastest-growing theatre. China is the standout growth market, with our analysis projecting a 9.2% CAGR through 2036, driven by rapid pet ownership growth, veterinary hospital expansion, and growing diagnostic testing adoption. South Korea (7.6% CAGR) and India are also emerging as significant markets. The region benefits from greenfield placement opportunities, as pet ownership grows faster than veterinary diagnostic infrastructure, creating demand for affordable, multi-species capable instruments.
Competitive Strategies and Recent Developments
The competitive landscape is characterized by a mix of established global players and regional specialists, with consolidation and technological innovation as key strategic themes.
Product Innovation and Launches: In December 2025, a leading animal health company launched a next-generation point-of-care hematology analyzer at VMX 2025 in Orlando, using viscoelastic focusing (VEF) and AI-powered algorithms to deliver fast, accurate CBC analysis. This launch intensifies competition and drives innovation, encouraging a shift toward faster, low-maintenance hematology solutions.
Mergers and Acquisitions: Companies are pursuing M&A to expand diagnostic capabilities. Notable examples include the acquisition of Scandinavian Micro Biodevices to strengthen point-of-care diagnostics portfolios, and the acquisition of ezyVet to enhance data management and diagnostic integration, reflecting a trend toward tech-driven consolidation.
Connected Diagnostic Ecosystems: Companies are investing in platforms that integrate hematology, chemistry, and urinalysis results, creating practice management value beyond standalone instrument capability. This ecosystem strategy drives instrument suite procurement and enhances customer stickiness.
Geographic Expansion: Leading players are targeting emerging markets with affordable, multi-species capable analyzers, while also acquiring regional distributors to overcome service network gaps and improve after-sales support.
Value Chain and Supply Chain Risk Assessment
The veterinary blood analyser value chain comprises raw material suppliers, component manufacturers (e.g., fluidics, optics, electronics), instrument OEMs, software/AI developers, distributors, and end-users (clinics, laboratories).
Supply Chain Vulnerabilities: The industry is susceptible to disruptions in semiconductor supply (for electronic components) and specialized reagents. The COVID-19 pandemic exposed these vulnerabilities, prompting companies to diversify supplier bases and increase inventory buffers. Our primary research indicates that over 60% of manufacturers have now dual-sourced critical components.
Reagent Lock-In and Consumables: Proprietary cartridge and reagent systems create a recurring revenue stream but also lock in customers. This model is a double-edged sword: it ensures predictable revenue for manufacturers but can be a barrier for cost-sensitive clinics. We estimate that consumables account for 40-50% of total cost of ownership over a 5-year period.
Service and Support Networks: The ability to provide rapid technical support and reagent replenishment is a critical competitive differentiator. Companies that have invested in regional distribution and service infrastructure have gained market share, particularly in emerging markets.
Strategic White-Space Analysis
Our analysis identifies several under-penetrated opportunities for growth:
Emerging Market Greenfield Placements: Asia Pacific and Latin America present significant white space, as pet ownership grows faster than diagnostic infrastructure. Affordable, robust, multi-species analyzers with low maintenance requirements are needed.
Slide-Free Morphology and AI-Assisted Diagnostics: The development of slide-free cellular analysis technology that eliminates manual microscopy represents a transformative capability expansion for point-of-care diagnostics. Companies that can deliver accurate, user-friendly AI-assisted morphology will capture a premium segment.
Connected Diagnostic Ecosystems: Integrating hematology with chemistry, urinalysis, and imaging results on a single platform creates practice management value and drives instrument suite procurement. This is a key battleground for market leadership.
Livestock and Herd Health Management: While companion animals dominate, the livestock sector contributes significantly through disease surveillance and herd health management. Government funding for animal disease surveillance is a stable demand driver, particularly for high-throughput, ruggedized analyzers capable of processing many samples per hour.
Future Outlook and Strategic Recommendations
The veterinary blood analyser industry is poised for a decade of robust growth, with the market projected to reach USD 2.1 billion by 2030 and USD 4.1 billion by 2035 under optimistic scenarios. The key strategic imperatives for stakeholders are:
Invest in AI and Automation: To reduce the skill barrier and improve diagnostic accuracy, companies must embed AI-assisted cellular analysis into their platforms.
Expand Point-of-Care Offerings: The shift toward POC testing is irreversible; companies must offer compact, cartridge-based systems that deliver rapid, accurate results.
Build Service Networks in Emerging Markets: To capitalize on greenfield opportunities, companies must establish robust distribution and service infrastructure, potentially through acquisitions.
Prioritize Multi-Species Capability: The ability to calibrate for multiple species (companion, equine, bovine, exotic) from a single instrument is a key differentiator, particularly for reference laboratories and mixed practices.
Navigate Regulatory Pathways Efficiently: Early engagement with regulators and investment in quality systems are essential to reduce time-to-market and maintain clinician confidence.
In conclusion, the veterinary blood analyser market offers compelling growth opportunities for incumbents and new entrants alike, driven by demographic, technological, and institutional forces that are reshaping veterinary diagnostics worldwide.
Veterinary Blood Analyser Industry Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Veterinary Blood Analyser Industry REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2024
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 10.0% from 2020-2034
Segmentation
By Product
Benchtop/Laboratory Analyzers
Point-of-Care/In-Clinic Analyzers
Semi-Automated Analyzers
By Technology
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.1.1. Rising pet ownership and humanization of companion animals
3.1.2. Increased government funding for animal disease surveillance
3.1.3. Growing demand for preventive care and wellness screening
3.4.3. Distribution and after-sales service network gaps in emerging markets
CUSTOM INTELLIGENCE
Tailored for you
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Customized Evaluation of Competitive Landscape to Meet Your Needs
Ask for customization
Analyst at Providence Strategic Partners at Petaling Jaya
Jared Wan
I have received the report already. Thanks you for your help.it has been a pleasure working with you. Thank you again for a good quality report
Internationalization Director
Santiago Mejia Molina
Yes, as a matter of fact we are totally satisfied with both reports that we have purchased and will continue to do so during this process of the internationalization of our brand.
Head of Product Management and Marketing
Olaf Gleibe
We are using your report, and it gave us valuable information."
Regional Director, Marketing and Business Development
Lina Lim
We've received the report and have reviewed the content. Overall, it looks great and aligns closely with the data we can verify based on our industry knowledge.
VP of Sales
DIGGLE Representative
Thank you very much for sharing the report. I have reviewed it and I am very satisfied with the quality and the insights it provides. It will certainly be valuable for our internal discussions.
3.5.1. Veterinary technician staffing shortages in mature markets
3.5.2. Reagent lock-in and proprietary cartridge systems limiting switching
3.5.3. Price sensitivity in emerging markets
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. IMD Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Product
5.1.1. Benchtop/Laboratory Analyzers
5.1.2. Point-of-Care/In-Clinic Analyzers
5.1.3. Semi-Automated Analyzers
5.2. Market Analysis, Insights and Forecast - by Technology
5.2.1. 3-Part Differential Impedance
5.2.2. 5-Part Differential & Flow Cytometry
5.2.3. AI-Powered Image Recognition
5.3. Market Analysis, Insights and Forecast - by Animal Type
5.3.1. Companion Animals
5.3.2. Equine
5.3.3. Large Animals
5.3.4. Exotic Animals
5.4. Market Analysis, Insights and Forecast - by End-User
5.4.1. Veterinary Clinics & Small Animal Practices
5.4.2. Veterinary Reference Laboratories
5.4.3. Research Institutes & Academic Centers
5.4.4. Animal Breeding Farms
5.5. Market Analysis, Insights and Forecast - by Application
5.5.1. Disease Diagnosis
5.5.2. Pre-Surgical Screening
5.5.3. Wellness Monitoring
5.5.4. Emergency Triage
5.6. Market Analysis, Insights and Forecast - by Region
5.6.1. North America
5.6.2. Europe
5.6.3. Asia Pacific
5.6.4. Latin America
5.6.5. Middle East & Africa
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Product
6.1.1. Benchtop/Laboratory Analyzers
6.1.2. Point-of-Care/In-Clinic Analyzers
6.1.3. Semi-Automated Analyzers
6.2. Market Analysis, Insights and Forecast - by Technology
6.2.1. 3-Part Differential Impedance
6.2.2. 5-Part Differential & Flow Cytometry
6.2.3. AI-Powered Image Recognition
6.3. Market Analysis, Insights and Forecast - by Animal Type
6.3.1. Companion Animals
6.3.2. Equine
6.3.3. Large Animals
6.3.4. Exotic Animals
6.4. Market Analysis, Insights and Forecast - by End-User
6.4.1. Veterinary Clinics & Small Animal Practices
6.4.2. Veterinary Reference Laboratories
6.4.3. Research Institutes & Academic Centers
6.4.4. Animal Breeding Farms
6.5. Market Analysis, Insights and Forecast - by Application
6.5.1. Disease Diagnosis
6.5.2. Pre-Surgical Screening
6.5.3. Wellness Monitoring
6.5.4. Emergency Triage
7. Europe Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Product
7.1.1. Benchtop/Laboratory Analyzers
7.1.2. Point-of-Care/In-Clinic Analyzers
7.1.3. Semi-Automated Analyzers
7.2. Market Analysis, Insights and Forecast - by Technology
7.2.1. 3-Part Differential Impedance
7.2.2. 5-Part Differential & Flow Cytometry
7.2.3. AI-Powered Image Recognition
7.3. Market Analysis, Insights and Forecast - by Animal Type
7.3.1. Companion Animals
7.3.2. Equine
7.3.3. Large Animals
7.3.4. Exotic Animals
7.4. Market Analysis, Insights and Forecast - by End-User
7.4.1. Veterinary Clinics & Small Animal Practices
7.4.2. Veterinary Reference Laboratories
7.4.3. Research Institutes & Academic Centers
7.4.4. Animal Breeding Farms
7.5. Market Analysis, Insights and Forecast - by Application
7.5.1. Disease Diagnosis
7.5.2. Pre-Surgical Screening
7.5.3. Wellness Monitoring
7.5.4. Emergency Triage
8. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Product
8.1.1. Benchtop/Laboratory Analyzers
8.1.2. Point-of-Care/In-Clinic Analyzers
8.1.3. Semi-Automated Analyzers
8.2. Market Analysis, Insights and Forecast - by Technology
8.2.1. 3-Part Differential Impedance
8.2.2. 5-Part Differential & Flow Cytometry
8.2.3. AI-Powered Image Recognition
8.3. Market Analysis, Insights and Forecast - by Animal Type
8.3.1. Companion Animals
8.3.2. Equine
8.3.3. Large Animals
8.3.4. Exotic Animals
8.4. Market Analysis, Insights and Forecast - by End-User
8.4.1. Veterinary Clinics & Small Animal Practices
8.4.2. Veterinary Reference Laboratories
8.4.3. Research Institutes & Academic Centers
8.4.4. Animal Breeding Farms
8.5. Market Analysis, Insights and Forecast - by Application
8.5.1. Disease Diagnosis
8.5.2. Pre-Surgical Screening
8.5.3. Wellness Monitoring
8.5.4. Emergency Triage
9. Latin America Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Product
9.1.1. Benchtop/Laboratory Analyzers
9.1.2. Point-of-Care/In-Clinic Analyzers
9.1.3. Semi-Automated Analyzers
9.2. Market Analysis, Insights and Forecast - by Technology
9.2.1. 3-Part Differential Impedance
9.2.2. 5-Part Differential & Flow Cytometry
9.2.3. AI-Powered Image Recognition
9.3. Market Analysis, Insights and Forecast - by Animal Type
9.3.1. Companion Animals
9.3.2. Equine
9.3.3. Large Animals
9.3.4. Exotic Animals
9.4. Market Analysis, Insights and Forecast - by End-User
9.4.1. Veterinary Clinics & Small Animal Practices
9.4.2. Veterinary Reference Laboratories
9.4.3. Research Institutes & Academic Centers
9.4.4. Animal Breeding Farms
9.5. Market Analysis, Insights and Forecast - by Application
9.5.1. Disease Diagnosis
9.5.2. Pre-Surgical Screening
9.5.3. Wellness Monitoring
9.5.4. Emergency Triage
10. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Product
10.1.1. Benchtop/Laboratory Analyzers
10.1.2. Point-of-Care/In-Clinic Analyzers
10.1.3. Semi-Automated Analyzers
10.2. Market Analysis, Insights and Forecast - by Technology
10.2.1. 3-Part Differential Impedance
10.2.2. 5-Part Differential & Flow Cytometry
10.2.3. AI-Powered Image Recognition
10.3. Market Analysis, Insights and Forecast - by Animal Type
10.3.1. Companion Animals
10.3.2. Equine
10.3.3. Large Animals
10.3.4. Exotic Animals
10.4. Market Analysis, Insights and Forecast - by End-User
10.4.1. Veterinary Clinics & Small Animal Practices
10.4.2. Veterinary Reference Laboratories
10.4.3. Research Institutes & Academic Centers
10.4.4. Animal Breeding Farms
10.5. Market Analysis, Insights and Forecast - by Application
10.5.1. Disease Diagnosis
10.5.2. Pre-Surgical Screening
10.5.3. Wellness Monitoring
10.5.4. Emergency Triage
11. Competitive Analysis
11.1. Company Profiles
11.1.1. IDEXX Laboratories
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. Zoetis
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. Heska
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. Antech Diagnostics
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. Drew Scientific
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. Siemens Healthineers
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. Nihon Kohden
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. Sysmex
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. Hitachi High-Tech
11.1.9.1. Company Overview
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.1.10. Fujifilm
11.1.10.1. Company Overview
11.1.10.2. Products
11.1.10.3. Company Financials
11.1.10.4. SWOT Analysis
11.1.11. Scil Animal Care
11.1.11.1. Company Overview
11.1.11.2. Products
11.1.11.3. Company Financials
11.1.11.4. SWOT Analysis
11.1.12. Woodley Equipment Company
11.1.12.1. Company Overview
11.1.12.2. Products
11.1.12.3. Company Financials
11.1.12.4. SWOT Analysis
11.1.13. Boule Medical
11.1.13.1. Company Overview
11.1.13.2. Products
11.1.13.3. Company Financials
11.1.13.4. SWOT Analysis
11.1.14. Horiba
11.1.14.1. Company Overview
11.1.14.2. Products
11.1.14.3. Company Financials
11.1.14.4. SWOT Analysis
11.1.15. EKF Diagnostics
11.1.15.1. Company Overview
11.1.15.2. Products
11.1.15.3. Company Financials
11.1.15.4. SWOT Analysis
11.1.16. bioMérieux
11.1.16.1. Company Overview
11.1.16.2. Products
11.1.16.3. Company Financials
11.1.16.4. SWOT Analysis
11.1.17. BPC BioSed
11.1.17.1. Company Overview
11.1.17.2. Products
11.1.17.3. Company Financials
11.1.17.4. SWOT Analysis
11.1.18. Samsung Medison
11.1.18.1. Company Overview
11.1.18.2. Products
11.1.18.3. Company Financials
11.1.18.4. SWOT Analysis
11.1.19. Transasia Bio-Medicals
11.1.19.1. Company Overview
11.1.19.2. Products
11.1.19.3. Company Financials
11.1.19.4. SWOT Analysis
11.1.20. Skanex
11.1.20.1. Company Overview
11.1.20.2. Products
11.1.20.3. Company Financials
11.1.20.4. SWOT Analysis
11.1.21. Mindray
11.1.21.1. Company Overview
11.1.21.2. Products
11.1.21.3. Company Financials
11.1.21.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
List of Figures
Figure 1: Global Veterinary Blood Analyser Industry Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America Veterinary Blood Analyser Industry Revenue (Billion), by Product 2026 & 2034
Figure 3: North America Veterinary Blood Analyser Industry Revenue Share (%), by Product 2026 & 2034
Figure 4: North America Veterinary Blood Analyser Industry Revenue (Billion), by Technology 2026 & 2034
Figure 5: North America Veterinary Blood Analyser Industry Revenue Share (%), by Technology 2026 & 2034
Figure 6: North America Veterinary Blood Analyser Industry Revenue (Billion), by Animal Type 2026 & 2034
Figure 7: North America Veterinary Blood Analyser Industry Revenue Share (%), by Animal Type 2026 & 2034
Figure 8: North America Veterinary Blood Analyser Industry Revenue (Billion), by End-User 2026 & 2034
Figure 9: North America Veterinary Blood Analyser Industry Revenue Share (%), by End-User 2026 & 2034
Figure 10: North America Veterinary Blood Analyser Industry Revenue (Billion), by Application 2026 & 2034
Figure 11: North America Veterinary Blood Analyser Industry Revenue Share (%), by Application 2026 & 2034
Figure 12: North America Veterinary Blood Analyser Industry Revenue (Billion), by Country 2026 & 2034
Figure 13: North America Veterinary Blood Analyser Industry Revenue Share (%), by Country 2026 & 2034
Figure 14: Europe Veterinary Blood Analyser Industry Revenue (Billion), by Product 2026 & 2034
Figure 15: Europe Veterinary Blood Analyser Industry Revenue Share (%), by Product 2026 & 2034
Figure 16: Europe Veterinary Blood Analyser Industry Revenue (Billion), by Technology 2026 & 2034
Figure 17: Europe Veterinary Blood Analyser Industry Revenue Share (%), by Technology 2026 & 2034
Figure 18: Europe Veterinary Blood Analyser Industry Revenue (Billion), by Animal Type 2026 & 2034
Figure 19: Europe Veterinary Blood Analyser Industry Revenue Share (%), by Animal Type 2026 & 2034
Figure 20: Europe Veterinary Blood Analyser Industry Revenue (Billion), by End-User 2026 & 2034
Figure 21: Europe Veterinary Blood Analyser Industry Revenue Share (%), by End-User 2026 & 2034
Figure 22: Europe Veterinary Blood Analyser Industry Revenue (Billion), by Application 2026 & 2034
Figure 23: Europe Veterinary Blood Analyser Industry Revenue Share (%), by Application 2026 & 2034
Figure 24: Europe Veterinary Blood Analyser Industry Revenue (Billion), by Country 2026 & 2034
Figure 25: Europe Veterinary Blood Analyser Industry Revenue Share (%), by Country 2026 & 2034
Figure 26: Asia Pacific Veterinary Blood Analyser Industry Revenue (Billion), by Product 2026 & 2034
Figure 27: Asia Pacific Veterinary Blood Analyser Industry Revenue Share (%), by Product 2026 & 2034
Figure 28: Asia Pacific Veterinary Blood Analyser Industry Revenue (Billion), by Technology 2026 & 2034
Figure 29: Asia Pacific Veterinary Blood Analyser Industry Revenue Share (%), by Technology 2026 & 2034
Figure 30: Asia Pacific Veterinary Blood Analyser Industry Revenue (Billion), by Animal Type 2026 & 2034
Figure 31: Asia Pacific Veterinary Blood Analyser Industry Revenue Share (%), by Animal Type 2026 & 2034
Figure 32: Asia Pacific Veterinary Blood Analyser Industry Revenue (Billion), by End-User 2026 & 2034
Figure 33: Asia Pacific Veterinary Blood Analyser Industry Revenue Share (%), by End-User 2026 & 2034
Figure 34: Asia Pacific Veterinary Blood Analyser Industry Revenue (Billion), by Application 2026 & 2034
Figure 35: Asia Pacific Veterinary Blood Analyser Industry Revenue Share (%), by Application 2026 & 2034
Figure 36: Asia Pacific Veterinary Blood Analyser Industry Revenue (Billion), by Country 2026 & 2034
Figure 37: Asia Pacific Veterinary Blood Analyser Industry Revenue Share (%), by Country 2026 & 2034
Figure 38: Latin America Veterinary Blood Analyser Industry Revenue (Billion), by Product 2026 & 2034
Figure 39: Latin America Veterinary Blood Analyser Industry Revenue Share (%), by Product 2026 & 2034
Figure 40: Latin America Veterinary Blood Analyser Industry Revenue (Billion), by Technology 2026 & 2034
Figure 41: Latin America Veterinary Blood Analyser Industry Revenue Share (%), by Technology 2026 & 2034
Figure 42: Latin America Veterinary Blood Analyser Industry Revenue (Billion), by Animal Type 2026 & 2034
Figure 43: Latin America Veterinary Blood Analyser Industry Revenue Share (%), by Animal Type 2026 & 2034
Figure 44: Latin America Veterinary Blood Analyser Industry Revenue (Billion), by End-User 2026 & 2034
Figure 45: Latin America Veterinary Blood Analyser Industry Revenue Share (%), by End-User 2026 & 2034
Figure 46: Latin America Veterinary Blood Analyser Industry Revenue (Billion), by Application 2026 & 2034
Figure 47: Latin America Veterinary Blood Analyser Industry Revenue Share (%), by Application 2026 & 2034
Figure 48: Latin America Veterinary Blood Analyser Industry Revenue (Billion), by Country 2026 & 2034
Figure 49: Latin America Veterinary Blood Analyser Industry Revenue Share (%), by Country 2026 & 2034
Figure 50: Middle East & Africa Veterinary Blood Analyser Industry Revenue (Billion), by Product 2026 & 2034
Figure 51: Middle East & Africa Veterinary Blood Analyser Industry Revenue Share (%), by Product 2026 & 2034
Figure 52: Middle East & Africa Veterinary Blood Analyser Industry Revenue (Billion), by Technology 2026 & 2034
Figure 53: Middle East & Africa Veterinary Blood Analyser Industry Revenue Share (%), by Technology 2026 & 2034
Figure 54: Middle East & Africa Veterinary Blood Analyser Industry Revenue (Billion), by Animal Type 2026 & 2034
Figure 55: Middle East & Africa Veterinary Blood Analyser Industry Revenue Share (%), by Animal Type 2026 & 2034
Figure 56: Middle East & Africa Veterinary Blood Analyser Industry Revenue (Billion), by End-User 2026 & 2034
Figure 57: Middle East & Africa Veterinary Blood Analyser Industry Revenue Share (%), by End-User 2026 & 2034
Figure 58: Middle East & Africa Veterinary Blood Analyser Industry Revenue (Billion), by Application 2026 & 2034
Figure 59: Middle East & Africa Veterinary Blood Analyser Industry Revenue Share (%), by Application 2026 & 2034
Figure 60: Middle East & Africa Veterinary Blood Analyser Industry Revenue (Billion), by Country 2026 & 2034
Figure 61: Middle East & Africa Veterinary Blood Analyser Industry Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Global Veterinary Blood Analyser Industry Revenue Billion Forecast, by Product 2020 & 2034
Table 2: Global Veterinary Blood Analyser Industry Revenue Billion Forecast, by Technology 2020 & 2034
Table 3: Global Veterinary Blood Analyser Industry Revenue Billion Forecast, by Animal Type 2020 & 2034
Table 4: Global Veterinary Blood Analyser Industry Revenue Billion Forecast, by End-User 2020 & 2034
Table 5: Global Veterinary Blood Analyser Industry Revenue Billion Forecast, by Application 2020 & 2034
Table 6: Global Veterinary Blood Analyser Industry Revenue Billion Forecast, by Region 2020 & 2034
Table 7: North America Veterinary Blood Analyser Industry Revenue Billion Forecast, by Product 2020 & 2034
Table 8: North America Veterinary Blood Analyser Industry Revenue Billion Forecast, by Technology 2020 & 2034
Table 9: North America Veterinary Blood Analyser Industry Revenue Billion Forecast, by Animal Type 2020 & 2034
Table 10: North America Veterinary Blood Analyser Industry Revenue Billion Forecast, by End-User 2020 & 2034
Table 11: North America Veterinary Blood Analyser Industry Revenue Billion Forecast, by Application 2020 & 2034
Table 12: North America Veterinary Blood Analyser Industry Revenue Billion Forecast, by Country 2020 & 2034
Table 13: USA Veterinary Blood Analyser Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 14: Canada Veterinary Blood Analyser Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 15: Mexico Veterinary Blood Analyser Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 16: Europe Veterinary Blood Analyser Industry Revenue Billion Forecast, by Product 2020 & 2034
Table 17: Europe Veterinary Blood Analyser Industry Revenue Billion Forecast, by Technology 2020 & 2034
Table 18: Europe Veterinary Blood Analyser Industry Revenue Billion Forecast, by Animal Type 2020 & 2034
Table 19: Europe Veterinary Blood Analyser Industry Revenue Billion Forecast, by End-User 2020 & 2034
Table 20: Europe Veterinary Blood Analyser Industry Revenue Billion Forecast, by Application 2020 & 2034
Table 21: Europe Veterinary Blood Analyser Industry Revenue Billion Forecast, by Country 2020 & 2034
Table 22: Germany Veterinary Blood Analyser Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 23: UK Veterinary Blood Analyser Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 24: France Veterinary Blood Analyser Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 25: Italy Veterinary Blood Analyser Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 26: Spain Veterinary Blood Analyser Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 27: Asia Pacific Veterinary Blood Analyser Industry Revenue Billion Forecast, by Product 2020 & 2034
Table 28: Asia Pacific Veterinary Blood Analyser Industry Revenue Billion Forecast, by Technology 2020 & 2034
Table 29: Asia Pacific Veterinary Blood Analyser Industry Revenue Billion Forecast, by Animal Type 2020 & 2034
Table 30: Asia Pacific Veterinary Blood Analyser Industry Revenue Billion Forecast, by End-User 2020 & 2034
Table 31: Asia Pacific Veterinary Blood Analyser Industry Revenue Billion Forecast, by Application 2020 & 2034
Table 32: Asia Pacific Veterinary Blood Analyser Industry Revenue Billion Forecast, by Country 2020 & 2034
Table 33: China Veterinary Blood Analyser Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 34: Japan Veterinary Blood Analyser Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 35: South Korea Veterinary Blood Analyser Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 36: India Veterinary Blood Analyser Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 37: Australia Veterinary Blood Analyser Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 38: Latin America Veterinary Blood Analyser Industry Revenue Billion Forecast, by Product 2020 & 2034
Table 39: Latin America Veterinary Blood Analyser Industry Revenue Billion Forecast, by Technology 2020 & 2034
Table 40: Latin America Veterinary Blood Analyser Industry Revenue Billion Forecast, by Animal Type 2020 & 2034
Table 41: Latin America Veterinary Blood Analyser Industry Revenue Billion Forecast, by End-User 2020 & 2034
Table 42: Latin America Veterinary Blood Analyser Industry Revenue Billion Forecast, by Application 2020 & 2034
Table 43: Latin America Veterinary Blood Analyser Industry Revenue Billion Forecast, by Country 2020 & 2034
Table 44: Brazil Veterinary Blood Analyser Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 45: Argentina Veterinary Blood Analyser Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 46: Middle East & Africa Veterinary Blood Analyser Industry Revenue Billion Forecast, by Product 2020 & 2034
Table 47: Middle East & Africa Veterinary Blood Analyser Industry Revenue Billion Forecast, by Technology 2020 & 2034
Table 48: Middle East & Africa Veterinary Blood Analyser Industry Revenue Billion Forecast, by Animal Type 2020 & 2034
Table 49: Middle East & Africa Veterinary Blood Analyser Industry Revenue Billion Forecast, by End-User 2020 & 2034
Table 50: Middle East & Africa Veterinary Blood Analyser Industry Revenue Billion Forecast, by Application 2020 & 2034
Table 51: Middle East & Africa Veterinary Blood Analyser Industry Revenue Billion Forecast, by Country 2020 & 2034
Table 52: South Africa Veterinary Blood Analyser Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 53: UAE Veterinary Blood Analyser Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1What is the current market size of the veterinary blood analyser industry?
Our proprietary research values the global veterinary blood analyser market at **USD 1.2 billion in 2024**, with a projected growth to **USD 2.1 billion by 2030** at a **CAGR of 10.0%**. This growth is driven by rising pet ownership, preventive care adoption, and technological advancements in AI-powered diagnostics.
2Which region dominates the veterinary blood analyser market?
North America leads the market, accounting for **52.9% of global revenue in 2024**, supported by an extensive network of reference laboratories, high pet healthcare spending, and early adoption of advanced diagnostic technologies. However, Asia Pacific is the fastest-growing region, with China projected to grow at a **9.2% CAGR** through 2036.
3What are the key trends shaping the veterinary blood analyser industry?
Three key trends are reshaping the industry: (1) the shift from benchtop to point-of-care analyzers for real-time results, (2) the integration of AI for cellular morphology and slide-free analysis, and (3) the development of connected diagnostic ecosystems that integrate hematology, chemistry, and urinalysis on a single platform.
4What are the main challenges faced by veterinary blood analyser manufacturers?
Manufacturers face challenges including **high instrument acquisition costs** (a barrier for smaller clinics), **stringent regulatory approvals** (FDA Class II, CE-IVDR), and **service network gaps** in emerging markets. Additionally, veterinary technician shortages in mature markets constrain testing volumes.
5Which end-user segment holds the largest share in the veterinary blood analyser market?
Veterinary clinics and small animal practices dominate, holding **approximately 58% share in 2025**, driven by the proliferation of in-clinic diagnostics and point-of-care testing. Veterinary reference laboratories are the second-largest segment, projected to account for **41.5% of the market by 2035**.
Methodology
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
70–80% of the research effort was dedicated to primary research, engaging directly with industry stakeholders across the value chain. This included in-depth interviews with 150+ executives from veterinary clinics, reference laboratories, diagnostic equipment manufacturers, and distributors.
We targeted four specific company types: (1) hematology analyzer OEMs, (2) veterinary reference laboratory chains, (3) companion animal veterinary hospitals and clinics, and (4) regional diagnostic distributors. This segmentation ensured a comprehensive view of supply-side capabilities and demand-side requirements.
Stakeholder job titles interviewed included Chief Veterinary Officers, Laboratory Directors, Procurement Managers, and Clinical Practice Owners. These roles were selected to capture strategic, operational, and purchasing perspectives.
We also engaged with regulatory bodies and industry associations such as the American Veterinary Medical Association (AVMA), the World Organisation for Animal Health (WOAH), and the U.S. Department of Agriculture (USDA) to validate regulatory and funding trends.
Quantitative metrics collected during interviews included annual testing volumes per clinic, average cost per CBC test, instrument replacement cycles, and consumable consumption rates. These metrics formed the basis for bottom-up market sizing.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Chief Veterinary Officer
30%
Laboratory Director
25%
Procurement Manager
25%
Clinical Practice Owner
20%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Hematology Analyzer OEMs
35%
Veterinary Reference Laboratories
25%
Companion Animal Clinics & Hospitals
25%
Diagnostic Distributors
15%
Secondary Research & Industry Benchmarking
20–30% of the research effort involved secondary research, triangulating data from official multilateral sources, government agencies, and recognized non-profit trade associations. Key sources included:
American Pet Products Association (APPA) for pet ownership statistics.
USDA National Animal Health Laboratory Network (NAHLN) for funding and surveillance data.
Congress.gov for appropriations and legislation tracking.
World Organisation for Animal Health (WOAH) for global veterinary service performance data.
U.S. Food and Drug Administration (FDA) for medical device regulatory pathways.
We utilized standard financial databases including Bloomberg, Factiva, Hoovers, and PitchBook to analyze corporate financials, M&A activity, and market entry strategies. These were cross-referenced with official .gov and .org sources to ensure data integrity.
Every report is updated to the date of purchase, incorporating the latest available data from these sources.
Demand Modeling & Market Estimation
We employed both top-down and bottom-up methodologies simultaneously, validating findings through multi-level data triangulation.
Bottom-up approach: We built the market size by estimating the installed base of veterinary blood analysers across end-user segments (clinics, laboratories, research institutions) in each region, multiplied by average annual consumable spending and instrument replacement values. This was validated against primary interview data on testing volumes and pricing.
Top-down approach: We cross-referenced our bottom-up estimates with aggregated industry revenue data from public company filings and trade association reports, ensuring consistency.
Key quantitative metrics used in the bottom-up calculation included:
Number of veterinary clinics and hospitals per region (sourced from AVMA, FECAVA, and national veterinary boards).
Average annual CBC tests per clinic (derived from primary interviews, ranging from 1,200 to 5,000 depending on clinic size).
Average selling price (ASP) per analyzer and consumable cost per test.
Instrument replacement cycle (5–8 years, varying by region and product tier).
Multi-level data triangulation was achieved by comparing primary interview data with secondary source benchmarks, and reconciling discrepancies through follow-up interviews.
Data Accuracy & Quality Check
We guarantee an estimated data accuracy level of 85–90%, achieved through rigorous validation protocols.
Every data point was cross-verified with at least two independent sources (primary and secondary). Where discrepancies arose, we conducted additional interviews to resolve them.
Quality control procedures included: (1) a peer-review process for all analyst projections, (2) a consistency check against historical market data and growth trends, and (3) a final audit by our Senior Research Director.
We maintain a transparent audit trail for all data sources, ensuring traceability and reproducibility. This commitment to quality is why our reports are trusted by industry leaders for strategic decision-making.
North America feed grade calcium phosphate market to reach $2.09 Bn by 2034, growing at 2.5% CAGR. Explore MCP dominance, poultry demand, and supply trends.
The global pet care products market is valued at $181.9B in 2025 and is projected to reach $283.7B by 2033, growing at a CAGR of 5.9%.
Nov 2026|200 pages
$2900.00
Vietnam animal feed market valued at 1.76 billion in 2024, growing at 3.6% CAGR to 2030. Analyze product, livestock, and competitive trends.
Nov 2026|180 pages
$2900.00
Italy veterinary healthcare market is valued at USD 1.69 billion in 2026, growing at 5.12% CAGR to reach USD 2.17 billion by 2031. Read our full analysis.