Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
Prosthetic Sockets Market by Product Type (Lower Extremity Sockets(Trans-Tibial, Trans-Femoral, Knee Disarticulation), Upper Extremity Sockets(Trans-Radial, Trans-Humeral, Shoulder Disarticulation), Socket Inserts & Volume Management Systems), by Material (Silicone, Polyurethane, Thermoplastic Elastomer, Carbon Fiber & Composites), by Fabrication Method (Conventional Plaster-Cast, CAD/CAM Milled, 3D Printed), by End-Use (Hospitals & Acute Rehabilitation, Outpatient Prosthetic Clinics, Mobile & Humanitarian Outreach), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Nordics), by Asia Pacific (China, India, Japan, South Korea), by Latin America (Brazil, Mexico, Argentina), by Middle East & Africa (South Africa, Saudi Arabia, UAE) Forecast 2026-2034
Executive Overview: The Prosthetic Socket Market in 2025
The prosthetic socket is the single most consequential interface in limb-loss care. It is the structural and biomechanical bridge between a residual limb and every distal component — knee, foot, hand or terminal device — and it determines whether advanced prosthetic hardware delivers real-world mobility or sits unused in a closet.
Prosthetic Sockets Market Market Size (In Billion)
2.0B
1.5B
1.0B
500.0M
0
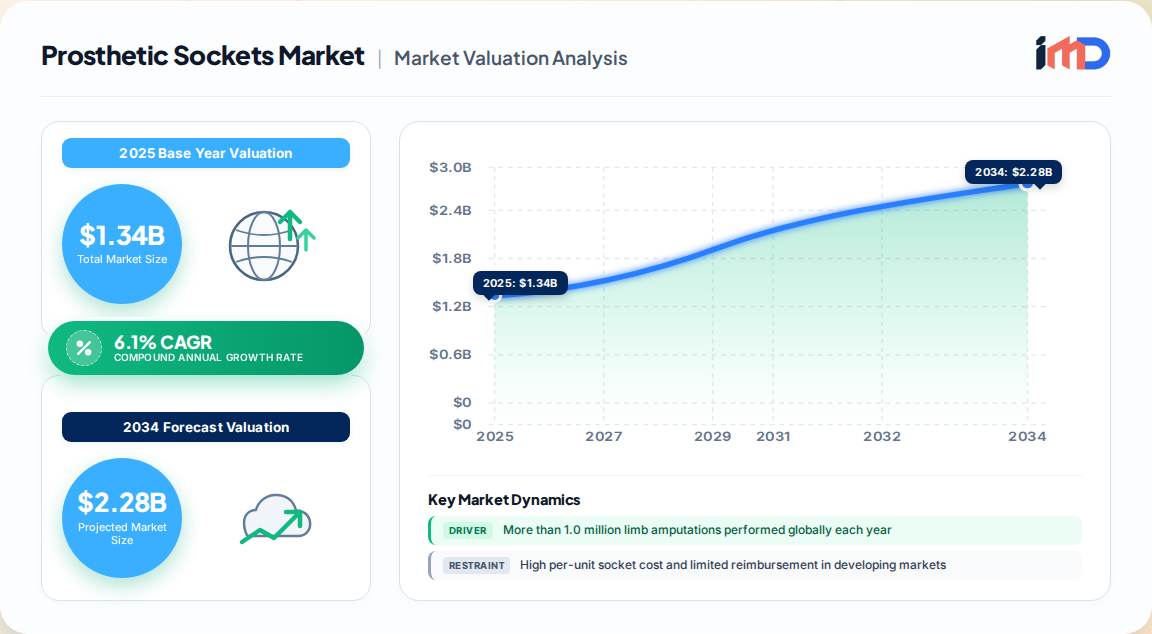
1.340 B
2025
1.422 B
2026
1.508 B
2027
1.600 B
2028
1.698 B
2029
1.802 B
2030
1.912 B
2031
Our proprietary primary research estimates the global prosthetic sockets market at USD 1.34 Billion in 2025, expanding at a 6.1% CAGR through 2034. Demand is anchored by more than 1.0 million limb amputations performed globally each year — roughly one every 30 seconds — alongside a congenital limb-difference population that requires repeated socket replacement across the life course.
Unlike terminal devices, sockets are consumable-adjacent. Residual limb volume fluctuates with weight, hydration, activity and disease progression, so a single patient may require 3 to 6 socket refits over a decade. That recurring replacement cycle, not initial fitting alone, is the core commercial engine of this market.
Base-year market value (2025): USD 1.34 Billion
Forecast CAGR (2026–2034): 6.1%
Dominant product line: Lower-extremity sockets
Fastest-growing material: Polyurethane and advanced silicone hybrid systems
Largest regional market: North America
Fastest-growing region: Asia Pacific
Key Market Drivers Reshaping Socket Demand
Rising amputation incidence tied to diabetes and vascular disease. Dysvascular complications remain the leading cause of lower-limb loss in high-income markets, creating a steadily replenishing patient pool with complex residual limb anatomy.
Reimbursement recognition for volume-management sockets. In March 2026, the U.S. Centers for Medicare & Medicaid Services finalized new HCPCS coding and reimbursement for lower-extremity prosthetic volume-management socket inserts — a landmark shift that converts an out-of-pocket upgrade into a reimbursable clinical necessity.
Digital and additive manufacturing. CAD/CAM socket design and 3D-printed sockets compress fabrication timelines from weeks to days, reduce material waste and enable patient-specific geometry that manual plaster modification cannot replicate.
Comfort-driven material innovation. Silicone, thermoplastic elastomer and polyurethane liner-socket systems now address pistoning, shear stress and skin breakdown — the leading causes of prosthetic abandonment.
Expanding rehabilitation infrastructure. Organized prosthetic provision, as framed by World Health Organization service standards, is expanding in middle-income markets, pulling socket demand into previously underserved geographies.
Restraints and Operational Challenges
High per-unit cost and out-of-pocket burden. A definitive lower-limb socket can represent a four-figure spend before any distal component is attached, constraining adoption where reimbursement is absent.
Critical shortage of trained prosthetists. WHO estimates only 1 in 10 people globally who need prosthetic and orthotic services receive appropriate products, largely due to workforce scarcity rather than device unavailability.
Reimbursement variability. Eligibility documentation requirements — such as functional-need criteria in U.S. Medicare lower-limb coverage — create administrative friction and delay fitting cycles.
Durability and fit degradation. Socket volume loss after amputation and residual limb atrophy force premature replacement, raising lifetime cost of care and complicating payer budgeting.
Fragmented, craft-dependent fabrication. Socket quality remains heavily dependent on individual practitioner skill, producing inconsistent clinical outcomes across providers.
Socket inserts, liners and volume-management systems
10%
Fastest growing
Lower-extremity sockets lead because walking, balance and fall prevention generate continuous functional requirements. Trans-tibial sockets dominate unit volume; trans-femoral sockets carry higher per-unit value due to ischial containment geometry and integrated suspension systems.
By Material
Silicone: Largest revenue share (~35%), favored for durability, skin compatibility and ease of cleaning.
Polyurethane: Fastest-growing (~7% CAGR), preferred for bony, scarred or irregular residual limbs due to pressure-absorbing flow characteristics.
Thermoplastic elastomer (TPE): Growing in cost-sensitive and pediatric applications.
Carbon fiber and advanced composites: Premium structural shells for active and high-load users.
By Fabrication Method
Conventional plaster-cast and hand-laminated sockets: Still the majority of global volume, particularly in low- and middle-income markets.
CAD/CAM digitally milled sockets: Standard of care in North America and Western Europe.
3D-printed sockets: The fastest-growing fabrication route, enabling distributed, on-site production at rehabilitation centers.
By End-Use Setting
Hospitals and acute rehabilitation: Largest share, driven by post-amputation inpatient fitting pathways.
Mobile and humanitarian outreach programs: Niche but strategically important for access expansion.
Regional Outlook
North America holds the largest revenue share, supported by mature reimbursement architecture, high CAD/CAM penetration and a concentrated prosthetist workforce. The 2026 CMS coding decision for volume-management socket inserts is expected to accelerate premium socket adoption.
Prosthetic Sockets Market Regional Market Share
Loading chart...
Europe is characterized by publicly funded prosthetic provision with strong service specifications — most notably England's 2025 prosthetic-service specification covering all ages with limb loss or limb difference. Germany and the Nordics lead in digital fabrication adoption.
Asia Pacific is the fastest-growing region, driven by large diabetic-amputation populations, expanding government investment in assistive technology and rising local manufacturing capability in China, India and South Korea.
Latin America and Middle East & Africa remain underpenetrated. WHO data indicates that in some low-income countries only 3% of people who need assistive products have access, versus up to 90% in high-income settings — a structural gap that defines the long-run volume opportunity.
Competitive Landscape and Strategic Developments
Socket manufacturing is moderately consolidated at the component-supply tier and highly fragmented at the clinical fabrication tier. Differentiation increasingly rests on the integrated liner-socket system rather than the shell alone.
2026: Ottobock launched the "iconiq" 3D-printed silicone liner, developed through digital planning and additive manufacturing for individualized fit.
2026: U.S. CMS finalized HCPCS coding and reimbursement for lower-extremity prosthetic volume-management socket inserts, recognizing advanced liner-socket technologies.
2026: CMS coding review acknowledged clinical differentiation of next-generation breathable and vented liner-socket systems, including Össur's Aerofit technology.
2025: England published an updated prosthetic-service specification covering all ages with limb loss or limb difference, embedding product provision within continuing rehabilitation.
2024: Össur launched the POWER KNEE actively powered microprocessor prosthesis, raising the performance bar for the socket-knee interface.
Value Chain Analysis
The socket value chain has five distinct tiers, each with different margin and bargaining dynamics.
3D scanning, CAD modelling, additive manufacturing services
Growing rapidly
Clinical fabrication & fitting
Casting, modification, alignment, delivery
Skill-dependent, locally fragmented
Post-fit care
Follow-up, adjustment, refit, replacement
Recurring, high-retention
The most defensible position is the integrated liner-socket platform, where material science, geometry and reimbursement coding converge. Suppliers that pair advanced materials with documented fitting support achieve stronger acceptance across hospital and rehabilitation networks.
Procurement and Sourcing Strategy Analysis
Reimbursement-first sourcing. Buyers should confirm HCPCS coding eligibility for volume-management and vented socket inserts before committing to premium platform adoption.
Dual-sourcing of liner materials. Silicone and polyurethane supply concentration creates single-point risk; qualifying two material grades per socket platform is prudent.
On-site digital fabrication. Investing in CAD/CAM milling or 3D printing capability reduces turnaround from weeks to days and lowers per-socket material waste.
Workforce co-investment. Because fitting quality determines outcomes, procurement contracts with manufacturer-provided clinician training materially improve cost-effectiveness.
Lifetime-cost contracting. Negotiating multi-year refit schedules rather than one-off device purchases aligns payer and provider incentives around sustained function.
Strategic White-Space Opportunities
Volume-management socket inserts in markets where reimbursement is newly established.
Pediatric socket systems that accommodate rapid limb growth through adjustable or modular geometry.
Point-of-care 3D printing at district-level rehabilitation facilities in Asia Pacific and Africa.
Sensor-instrumented sockets for real-time fit monitoring and remote clinical follow-up.
Breathable and vented liner-socket architectures targeting heat and moisture management in tropical climates.
Prosthetic Sockets Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Prosthetic Sockets Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 6.1% from 2020-2034
Segmentation
By Product Type
Lower Extremity Sockets
Trans-Tibial
Trans-Femoral
Knee Disarticulation
Upper Extremity Sockets
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.1.1. More than 1.0 million limb amputations performed globally each year
3.1.2. Rising diabetic and vascular amputation incidence
3.1.3. Reimbursement recognition for advanced volume-management socket inserts
3.1.4. Expanding prosthetic rehabilitation infrastructure in middle-income markets
3.2. Market Trends
3.2.1. Shift from plaster-cast to CAD/CAM and 3D-printed socket fabrication
3.2.2. Rising adoption of volume-management socket inserts following 2026 U.S. CMS reimbursement coding
1How big is the prosthetic sockets market in 2025?
Our primary research values the global prosthetic sockets market at USD 1.34 Billion in 2025, with lower-extremity sockets accounting for roughly 63% of product demand. The market is forecast to expand at a 6.1% CAGR through 2034.
2Why do lower-extremity sockets dominate the prosthetic sockets market?
Lower-extremity sockets represent about 63% of demand because walking, balance and fall prevention create continuous, non-discretionary functional requirements. Dysvascular amputation tied to diabetes also disproportionately affects the lower limb, sustaining high replacement volume.
3What is driving growth in the prosthetic sockets market?
Key drivers include more than 1.0 million annual limb amputations globally, U.S. CMS reimbursement finalization in 2026 for volume-management socket inserts, and rapid adoption of CAD/CAM and 3D-printed socket fabrication that shortens fitting cycles.
4Which region is the fastest-growing for prosthetic sockets?
Asia Pacific is the fastest-growing region, supported by large diabetic-amputation populations and expanding government investment in assistive technology. North America remains the largest market, holding roughly 34% of global revenue.
5How often do prosthetic socket users need a replacement?
Residual limb volume fluctuates with weight, hydration and activity, so many users require 3 to 6 socket refits over a decade. This recurring replacement cycle — not initial fitting alone — is the primary commercial engine of the market.
6Which materials are most used in prosthetic sockets?
Silicone holds the largest share at approximately 35% of liner and interface revenue, favored for durability and skin compatibility. Polyurethane is the fastest-growing material at around 7% CAGR, particularly for bony or scarred residual limbs.
Methodology
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
70–80% of total research effort is allocated to primary research, structured around direct engagement with prosthetic socket value-chain participants across North America, Europe, Asia Pacific, Latin America and the Middle East & Africa.
Interviews are conducted with prosthetic socket and liner manufacturers, contract fabrication and lamination specialists, CAD/CAM and additive manufacturing service providers, raw material suppliers of silicone, polyurethane, TPE and carbon fiber, and hospital and outpatient rehabilitation procurement teams.
Stakeholder designations interviewed include Chief Prosthetist / Clinical Director, Rehabilitation Department Procurement Manager, VP of Product Development (Prosthetics), and Materials and Supply Chain Lead.
Structured questionnaires capture unit volumes by socket type, material mix, refit frequency, pricing bands, reimbursement status and replacement cycle length, validated through follow-up depth interviews.
Raw Material Suppliers (Silicone, Polyurethane, TPE, Carbon Fiber)
17%
Hospital & Rehabilitation Procurement Teams
12%
Secondary Research & Industry Benchmarking
20–30% of research effort draws on official multilateral, governmental and non-profit technical sources, including WHO assistive technology statistics, UN Convention on the Rights of Persons with Disabilities reporting, and national health service specifications.
Financial filings and corporate disclosures are screened through Bloomberg, Factiva, Hoovers and PitchBook to validate manufacturer revenue mix, capital expenditure on digital fabrication and segment-level margin structure.
Trade and tariff data are cross-checked against official customs and statistical authorities where socket and liner components cross borders.
Published clinical and technical literature on residual limb volume management, suspension systems and socket fit outcomes is reviewed to benchmark clinical assumptions against commercial estimates.
No commercial market research publisher data is used at any stage of estimation.
Demand Modeling & Market Estimation
A bottom-up model builds market value from four quantitative anchors: (1) annual amputation and limb-difference incidence by country, (2) prosthetic fitting and retention rates by market, (3) average socket refit frequency per user per decade, and (4) average per-unit socket and insert price by product and material tier.
A top-down model reconciles the same market from reported prosthetic device revenue, isolating socket and insert value share from distal components and clinical services.
Multi-level data triangulation compares bottom-up and top-down outputs against primary interview price and volume checks, with variance tolerance held within 5%.
Segment-level splits by product, material, fabrication method and end-use setting are modeled separately to prevent aggregation error.
All figures are expressed in 2025 constant USD, with currency effects isolated from volume growth.
Data Accuracy & Quality Check
Estimated data accuracy is guaranteed at an 85–90% confidence level, consistent with primary-research-weighted estimation standards.
Every dataset passes a three-stage validation: respondent-level consistency checks, cross-segment reconciliation, and senior analyst review against clinical plausibility benchmarks.
Outlier responses are re-interviewed or down-weighted; any segment where primary coverage falls below a minimum respondent threshold is flagged and modeled with wider confidence bands.
Every report is updated to the date of purchase, incorporating the most recent reimbursement decisions, product launches and service specification changes.
Final projections are stress-tested against downside scenarios including reimbursement delay, material cost inflation and prosthetist workforce constraints.