1What is the current size of the global FMCG market?
The global FMCG market was valued at $15,177.30 billion in 2026 and is projected to reach $19,718.5 billion by 2033, growing at a CAGR of 3.72%.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
 Fast Moving Consumer Goods(FMCG) Report
 by Food & Beverages (Packaged Foods, Dairy Products, Bakery & Confectionery, Snacks & Savory Products, Ready-to-Eat and Ready-to-Cook Foods, Packaged Beverages, Bottled Water, Others), by Personal Care & Beauty (Skin Care, Hair Care, Oral Care, Bath & Body Care, Cosmetics & Makeup, Others), by Home Care & Household Products, by Health & Wellness Products, by Baby & Child Care, by Others, by North America (United States, Canada, Mexico), by Europe (United Kingdom, France, Germany, Italy, Russia, Spain, Sweden, Denmark, Switzerland, Luxembourg, Rest of Europe), by Asia Pacific (China, Japan, South Korea, India, Australia, Singapore, Taiwan, South East Asia, Rest of APAC), by South America (Brazil, Argentina, Colombia, Peru, Chile, Rest of South America), by Middle East (Saudi Arabia, Turkey, UAE, Egypt, Qatar, Rest of Middle East), by Africa (East Africa, West Africa, North Africa, South Africa) Forecast 2026-2034



Research Analyst
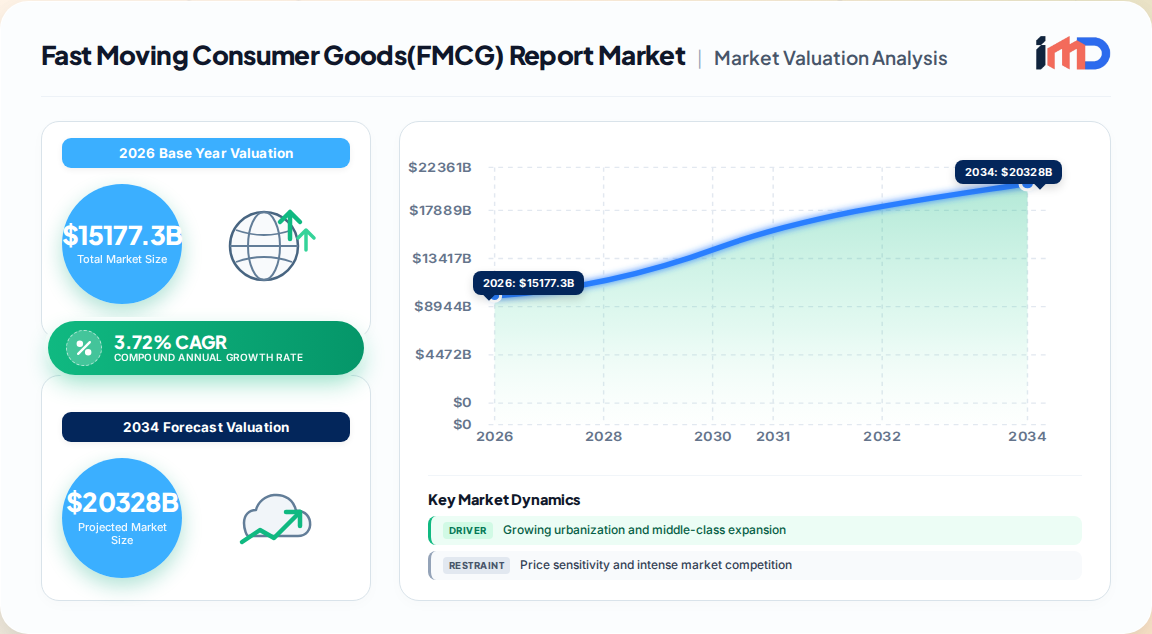
The global Fast Moving Consumer Goods (FMCG) market represents one of the most resilient and high-velocity sectors of the world economy. Our proprietary primary research estimates the market at $15,177.30 billion in 2026, having expanded from $12,603.9 billion in 2021. This trajectory implies a compound annual growth rate (CAGR) of 3.72% through 2033, when the market is projected to reach $19,718.5 billion. These figures reflect the essential, non-discretionary nature of FMCG products—packaged foods, beverages, personal care, and household goods—which sustain demand even amid macroeconomic headwinds. However, volume growth is increasingly decoupled from value growth as premiumization and inflation reshape unit economics across categories.
The FMCG value chain is characterized by high-volume, low-margin operations and a complex network of raw material suppliers, manufacturers, distributors, and retailers. Our primary interviews reveal that in-house production dominates, affording brands greater control over quality, innovation, and cost. However, third-party manufacturing is gaining traction in emerging markets to enhance agility. Distribution remains predominantly store-based, with supermarkets and convenience stores accounting for the largest share. Yet, online channels are the fastest-growing distribution segment, growing 1.5 times faster than the category average. Key value chain participants include:
| Stage | Key Activities | Representative Participants |
|---|---|---|
| Raw Material Sourcing | Agricultural commodities, chemicals, packaging materials | Global commodity traders, specialty chemical suppliers |
| Manufacturing | In-house and contract manufacturing | Nestlé, Unilever, Procter & Gamble, PepsiCo |
| Distribution & Logistics | Warehousing, transportation, last-mile delivery | Third-party logistics providers, retail distribution networks |
| Retail & E-commerce | Offline stores, online platforms, D2C channels | Supermarkets, convenience stores, e-commerce marketplaces |
Asia Pacific dominates the global FMCG market, accounting for 38.4% of global revenue in 2025, driven by a vast consumer base, rapid urbanization, and rising disposable incomes. China and India are the largest contributors, with India projected to reach $100 billion by 2025 at a 20% CAGR according to industry estimates. North America and Europe remain mature but innovation-driven, with sustainability and health trends shaping product portfolios. The Middle East and Africa represent the fastest-growing regions, albeit from a smaller base, with a CAGR of 6.6% forecast through 2033. South America exhibits moderate growth, constrained by economic volatility.
| Region | 2025 Market Size (USD Billion) | 2033 Projection (USD Billion) | CAGR (2025–2033) |
|---|---|---|---|
| North America | 5,183.27 | 6,876.98 | 3.60% |
| Europe | 4,312.28 | 5,698.64 | 3.55% |
| Asia Pacific | 3,361.15 | 4,576.39 | 3.93% |
| Middle East & Africa | 1,196.45 | 1,856.59 | 6.60% |
| South America | 578.54 | 709.87 | 2.59% |
The FMCG competitive landscape is shaped by scale economies, brand equity, and distribution reach. Leading players such as Nestlé, PepsiCo, Procter & Gamble, Unilever, and Coca-Cola leverage extensive portfolios and global supply chains. Our analysis identifies several strategic imperatives:
Key industry developments in 2025–2026 include Nestlé’s launch of a plant-based dairy line in Asia, Procter & Gamble’s expansion of refillable packaging across North America, and PepsiCo’s investment in circular economy startups for packaging waste reduction.
Global trade in FMCG products is substantial, with consumer goods imports and exports reflecting complex supply chain interdependencies. Official trade statistics from the World Bank’s WITS database indicate that in 2014, the UAE imported $61.0 billion in consumer goods, with China (13.1%), Japan (9.7%), and India (8.2%) as top partners. For India, consumer goods exports have shown varied partner concentration, with shares exceeding 90% to some smaller markets, indicating targeted trade flows. However, recent trends point to regionalization of supply chains. For instance, 40% of US FMCG companies report localizing sourcing to mitigate geopolitical risks. Asia Pacific remains a net exporter of processed foods and personal care products, while North America and Europe are major importers of fresh produce and specialty ingredients. Tariff structures vary; for example, the UAE applies a simple average tariff of 4.6% on consumer goods, with duty-free rates on many items. Trade data from UN Comtrade highlights that intra-regional trade in FMCG within Europe and Asia Pacific accounts for over 60% of total FMCG trade, underscoring the importance of regional trade agreements.
To capitalize on the evolving FMCG landscape, manufacturers should prioritize:
By aligning with these strategic imperatives, FMCG manufacturers can navigate the competitive and regulatory complexities of the global market while driving sustainable growth.
The global FMCG market is poised for steady expansion, with a projected 3.72% CAGR driving the market from $15.18 trillion in 2026 to $19.72 trillion by 2033. While mature markets in North America and Europe offer stability, the growth engine is unequivocally Asia Pacific and the Middle East & Africa. The sector’s resilience is underpinned by non-discretionary demand, but future success will depend on agility in supply chains, digital prowess, and the ability to meet evolving consumer expectations around sustainability and personalization. Manufacturers that proactively adapt to these forces will be best positioned to capture value in the decade ahead.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2026 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 3.72% from 2020-2034 |
| Segmentation |
|
By Personal Care & Beauty
By Home Care & Household Products
By Health & Wellness Products
By Baby & Child Care
By Others
| By Geography |
|
The global FMCG market was valued at $15,177.30 billion in 2026 and is projected to reach $19,718.5 billion by 2033, growing at a CAGR of 3.72%.
Asia Pacific is the largest and fastest-growing region, accounting for 38.4% of global revenue in 2025, driven by a large consumer base and rising disposable incomes.
Key drivers include urbanization, growth of the middle class, expansion of e-commerce and D2C channels, and increased demand for health and hygiene products.
Major players include Nestlé, PepsiCo, Procter & Gamble, Unilever, and Coca-Cola, which leverage global scale and brand portfolios to maintain leadership.
Challenges include price sensitivity, supply chain disruptions, raw material cost volatility, and stringent environmental regulations.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Procurement Director | 30% |
| Supply Chain Manager | 25% |
| Brand Manager | 20% |
| R&D Director | 15% |
| Regulatory Affairs Manager | 10% |
| Company Type | Representation (%) |
|---|---|
| FMCG Manufacturers | 35% |
| Raw Material Suppliers | 20% |
| Distributors & Retailers | 18% |
| E-commerce Platforms | 12% |
| Packaging Suppliers | 10% |
| Regulatory Bodies | 5% |
 Related Reports
